Updating Your Legal Technology Strategy

This article was inspired by the recent Law Firm Ambition webinar featuring Stephen Brown, Cathy Kirby and Stuart Whittle. 

Technology is changing the way law firms work, but building a successful technology strategy is about more than adopting the latest software or finding a new use for AI. That was one of the key themes of a recent Law Firm Ambition webinar, The Law Firm of Tomorrow: Updating Your Legal Technology Strategy featuring Stephen Brown, Cathy Kirby and Stuart Whittle.  

The discussion explored how firms can approach technology strategically, from AI and data management to legacy systems, client expectations, regulation and user adoption. One message came through clearly: technology should support the firm’s wider strategy, rather than becoming the strategy itself.  

AI is attracting attention, but it is only part of the picture 

AI is understandably dominating conversations about legal technology. During the webinar, lawyers were asked which area of legal technology would be their highest priority over the next 12 months: 
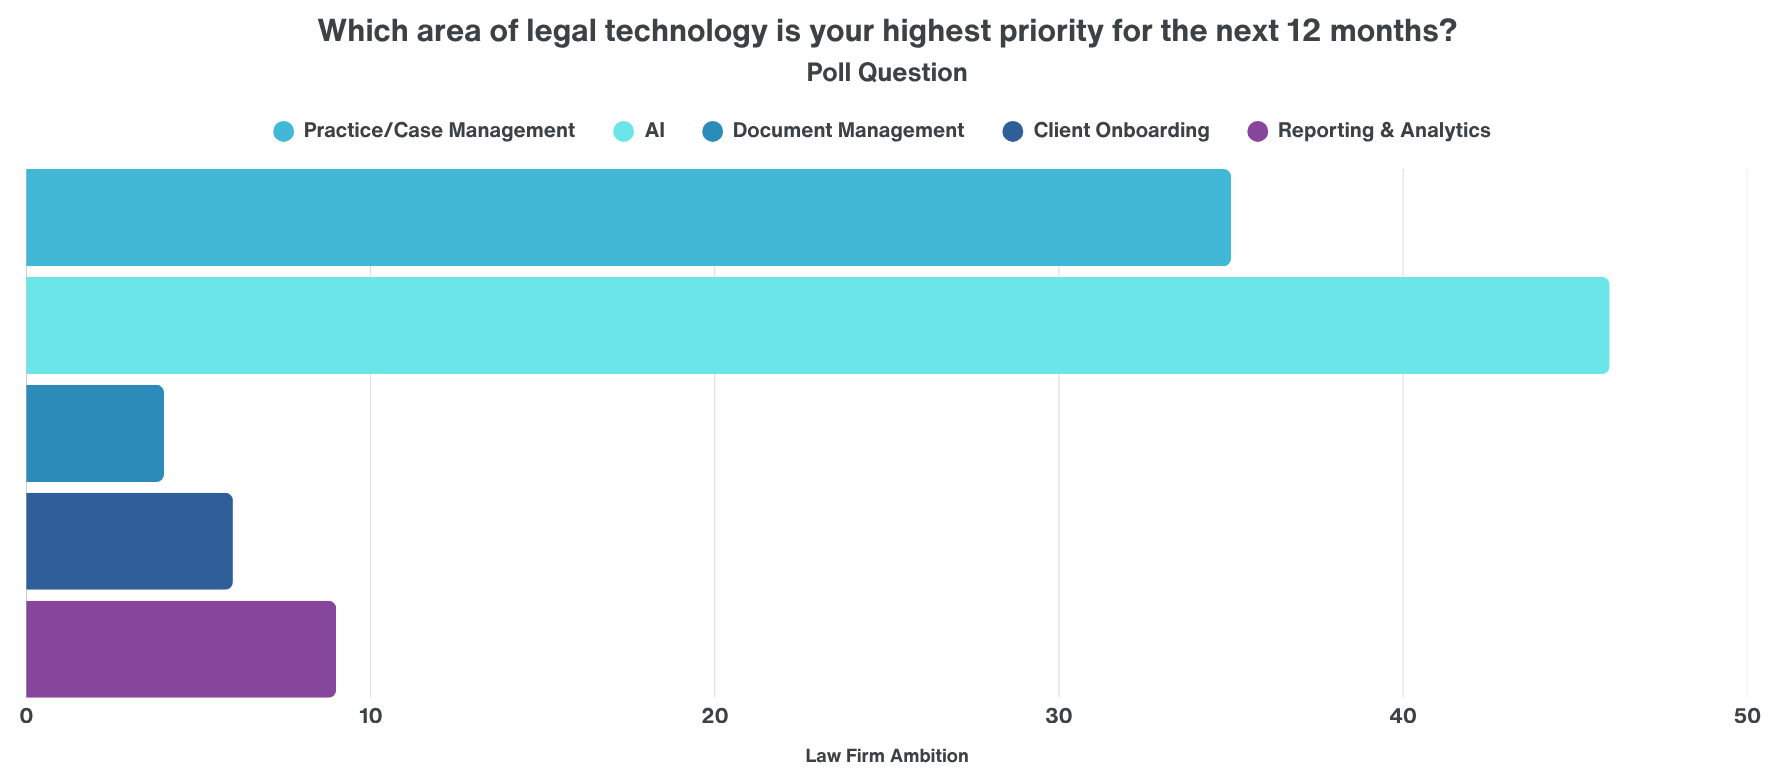
AI’s position at the top is perhaps unsurprising. There is considerable enthusiasm around what it can do, and new applications are appearing fast.  

However, the discussion also highlighted a potential risk: assuming AI is the answer before establishing what problem needs to be solved. It can be tempting to look at a new technology and immediately start thinking about how it could be used. A more strategic approach starts somewhere else. 

  • What is the firm trying to achieve? 
  • What problem is it trying to solve? 
  • Where does the firm create value? 
  • And what specific advantage could the technology provide? 

Technology is one part of a wider business strategy. It should have a clear purpose within it. 

Regulation needs to form part of the technology strategy 

The speed at which technology is developing creates another challenge for law firms. Products are changing quickly, while regulators are increasingly considering the risks associated with AI, data and other emerging technologies. Firms need to think about regulation and compliance alongside innovation. This is relevant regardless of the size of the firm. A smaller firm might assume that changes made by a major technology provider have little relevance to its own strategy. In reality, if Microsoft or another major provider changes how a product works, introduces a new AI capability or removes an existing feature, that change can have a direct impact on the systems a firm relies on. 

The pace of change has also altered. Technology decisions that might once have been considered over several years may now need to be reviewed over months. That has implications for IT teams, budgets, training and governance. It also means firms need to think about resilience. What happens if a product is discontinued, acquired or substantially changed? Having a clear technology strategy and governance framework makes it easier to respond when the market changes. 

Your clients should influence your technology strategy 

Technology decisions should not happen in isolation from the client experience.  

Reputation and experience remain the dominant reasons people choose a law firm, but clients increasingly expect to interact with businesses digitally.  

That could include: 

  • Online client onboarding 
  • Client portals 
  • Online payments 
  • Digital document sharing 
  • Greater visibility over pricing 
  • Digital communication and updates 

The right approach will depend on the firm’s clients and their expectations. A client portal may be extremely useful for one client group, while another may prefer a different way of communicating. The important point is to consider the whole client journey. If clients have different credentials for different systems, have to repeatedly enter the same information or encounter unnecessary friction between stages of their matter, individual pieces of technology may be working well while the overall experience is not. 

A technology strategy should therefore ask not only, “What does this system do?” but also, “What does this mean for our clients?” 

Start with the process, not the product 

One of the recurring themes from the webinar was the importance of understanding existing processes before introducing new technology. It is easy to become excited about a new product, particularly when vendors are demonstrating what it can do. But if the underlying process is unclear, technology may simply make an inefficient process more complicated. Before evaluating a new system, firms should understand: 

  • What the current process looks like 
  • Where the problems or delays occur 
  • What information is being used 
  • Who is responsible for each stage 
  • What the desired outcome should be 
  • How success will be measured 

This also highlights the importance of documenting processes. If a process is clearly mapped and understood, it becomes much easier to identify where technology could improve it. It also becomes easier to replace one component in the future without having to rethink the entire workflow. In other words, firms should know what they are trying to improve before deciding what technology they need. 

Data needs to be part of the conversation 

Many firms have accumulated systems over time, creating different data sources, processes and “data silos”. When systems do not communicate effectively, it can become difficult to obtain a complete picture of the business. This becomes increasingly important as firms look towards AI and analytics. Poor information at the start of a process will not suddenly become good information because it has been put into a sophisticated new system. 

Data should be categorised, organised and managed effectively. Firms considering major technology projects should understand what data they hold, where it sits, who can access it and how it moves between systems.  

The webinar discussion around legacy systems highlighted the same issue. New technology does not always work seamlessly with older systems, and firms need to consider how their existing technology infrastructure will support their future plans.  

The biggest technology project may be getting people to use it  

Technology implementation does not end when a new system goes live. In the webinar’s second poll, attendees were asked which technology project had been the most challenging for their firm. 
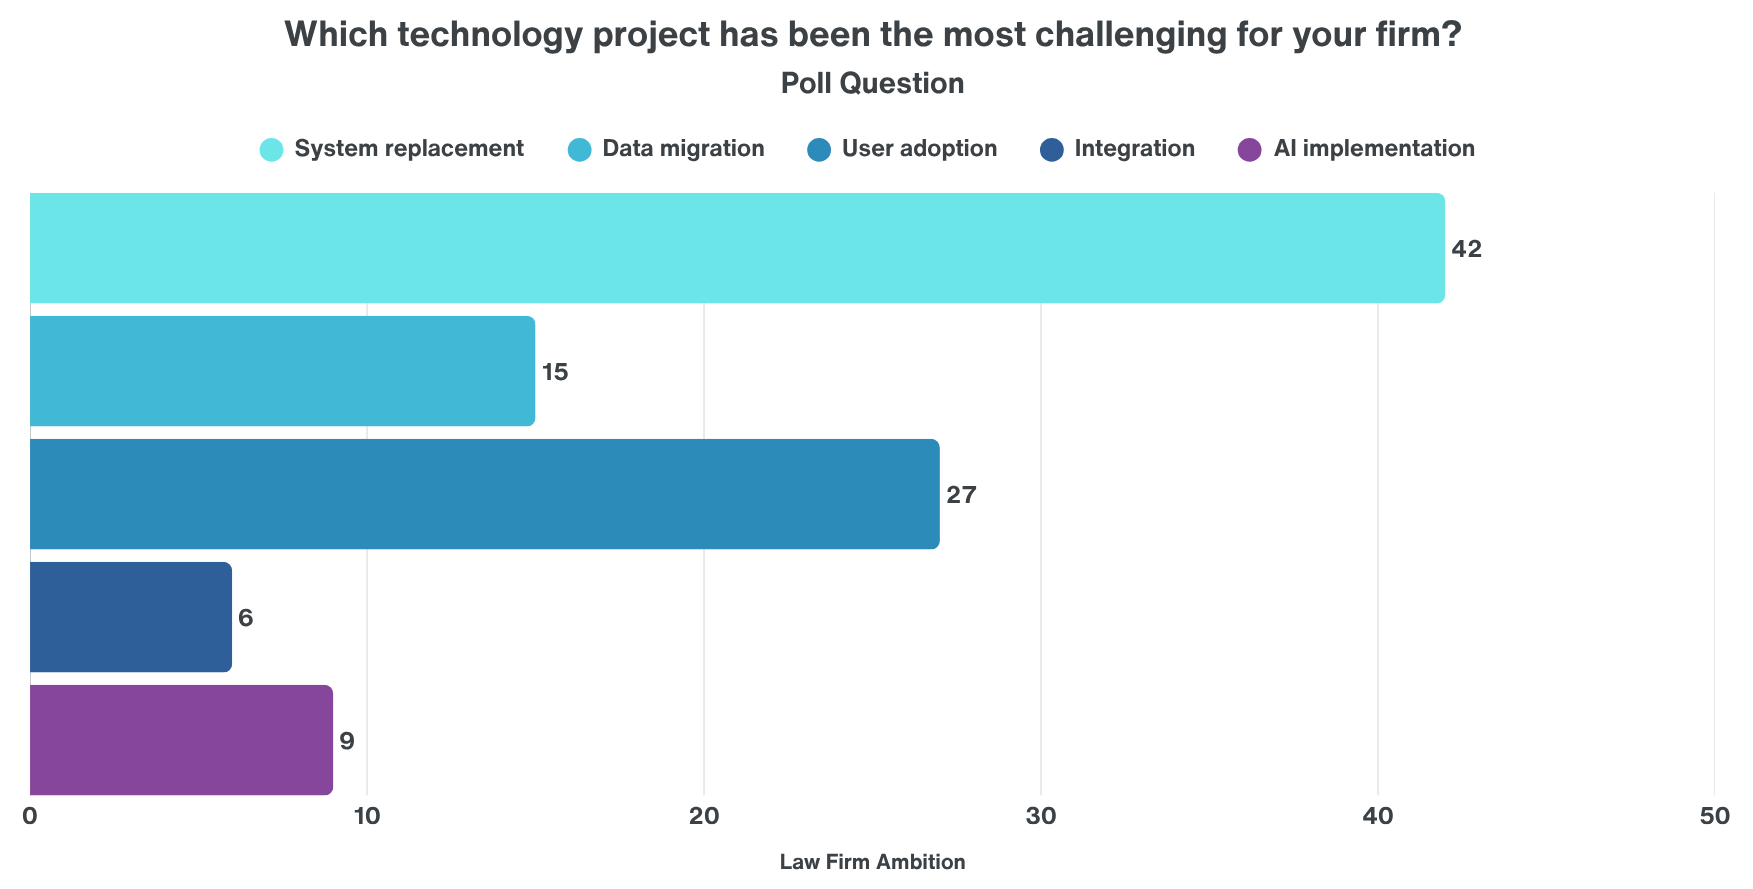
These challenges are closely connected. A new system can be technically successful but still fail to deliver its intended benefits if people do not understand how or why they should use it. User adoption needs to be measured by more than how many people have been moved onto a new system. Firms also need to consider whether people are using it correctly and whether they are getting the intended value from it.  

Training cannot be a one-off exercise either. Software changes, new features are introduced and processes evolve. Ongoing training and guidance can help ensure that the firm’s investment continues to deliver value. Most importantly, people need to understand why the change is happening. 

Explaining what employees need to do is important. Explaining why they are being asked to do it, and what the benefit will be, is equally important. Technology projects are ultimately people and business projects, supported by IT. 

AI governance needs to keep pace 

The increasing use of AI also creates new governance considerations. Firms need to think about who is responsible for AI use, what due diligence is required when selecting products, how employees should use AI and how the risks associated with different applications should be managed. This could include clear guidance around: 

  • Approved AI products 
  • Data that can and cannot be entered 
  • Checking AI-generated information 
  • Recording and sharing effective prompts or processes 
  • Staff training 
  • Client communication 
  • Responsibility and oversight 

The risks are not limited to dedicated AI products. Existing software is increasingly incorporating AI features, meaning firms may already be using AI without having specifically considered the implications. I-generated information should also be checked rather than assumed to be accurate. This is particularly important in legal work, where incorrect information can have serious consequences. A technology strategy needs to consider both what AI can do and how its use will be controlled. 

Confidence in existing systems remains a concern 

Perhaps the clearest indication that firms need to think strategically about their technology came from the webinar’s third poll. Attendees were asked how confident they were that their current systems would support their firm’s growth plans over the next three years. 
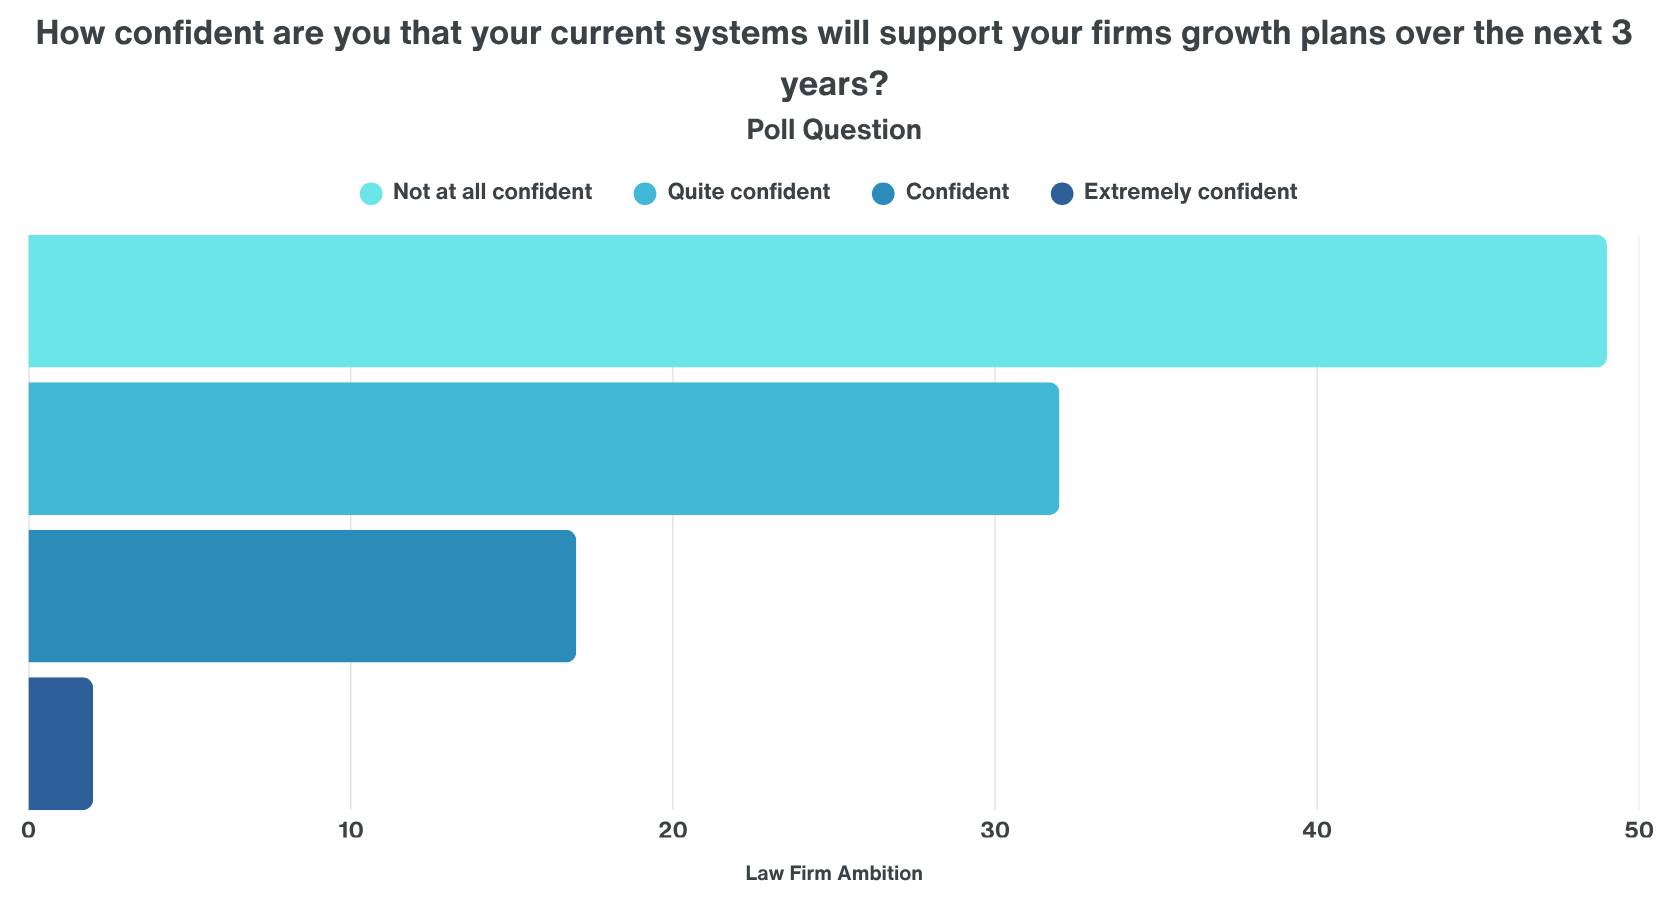
The result reflects a challenge facing many firms: technology debt. Legacy systems can continue to perform an important role, but they can also restrict what a firm is able to do next. At the same time, replacing core systems is rarely a straightforward exercise. 

There is a balance to be found between maintaining systems that work today and investing in the infrastructure needed for tomorrow. 

The law firm of tomorrow needs a plan for today 

The pace of technological change is unlikely to slow down. There will continue to be new AI products, new software integrations and new ways of working. Some will provide genuine value. Others may not solve the problems firms actually have.  

The firms best placed to respond will not necessarily be those adopting the most technology. They will be those that understand their business, their clients, their data and their processes well enough to make informed decisions about where technology can help. That means having a clear plan. Before introducing a new system or AI application, firms should be able to answer: 

  • What problem are we trying to solve? 
  • How does this support our wider business strategy? 
  • What will it mean for our clients? 
  • What data will it use? 
  • What are the regulatory and security considerations? 
  • How will we train our people? 
  • How will we measure whether it has worked? 
  • And perhaps most importantly: 
  • What happens if the technology changes or disappears? 

The law firm of tomorrow will certainly use technology differently from the law firm of today. But successful technology strategy is not about chasing every new development. It is about making deliberate choices that support the firm’s people, processes, clients and long-term objectives. 

For law firms reviewing their technology strategy, getting the foundations right including clear processes, effective data management and well-defined financial workflows, can be just as important as deciding which new technology to adopt. 

Don’t miss the next webinar from Law Firm Ambition, ‘Pricing and project management, the winning combination’ on Thursday 26th November at 9.30am. Register here

Early bird tickets are now available for the Law Firm Ambition Annual Conference 2027

Join industry experts in Leeds for a day of practical insights, thought-provoking discussions and valuable networking, with a focus on helping law firms achieve sustainable growth and long-term success. 
Yes, I want early bird tickets
Back to Blogs

Client Testimonial

“Our partnership with Cashroom has been an essential pillar of SP Solicitors. Compliance with the SRA Accounts Rules is not something a firm can get wrong and knowing our client account is in expert hands means my time goes where it belongs, with my clients.

Cashroom is a true partner, fully integrated into the way the firm runs. They understand how I work and the pace I work at, and they match it. Payments are processed promptly, reconciliations are always in order, and I never have to second guess our compliance position. As the firm grows, I know their support will grow with us. That confidence is worth a great deal.”

SP Solicitors


Succession Planning: Why Law Firms Should Start the Conversation Early

Guest blogger: David Johnstone

Succession planning is often something law firms think about when an event is approaching. A partner is preparing to retire. Someone wants to sell their interest in the business. A merger is being considered. By that point, however, some of the available options may already have disappeared.

Succession planning is most effective when it is considered well before there is any immediate need to act. Rather than being a response to a particular event, it can form part of the firm’s normal strategic planning, alongside discussion about growth, investment, people and financial performance.

For partners and boards, regularly asking what the future ownership and structure of the firm might look like can create considerably more flexibility when the time eventually comes to make a change.

Succession should be a part of the conversation

Succession does not necessarily mean retirement. It can involve a partner reducing their role, bringing in a new equity partner, transferring a particular area of work, restructuring the ownership of the firm, merging with another practice or eventually passing the business on to another firm.

The important point is that these possibilities are much easier to consider when there is no immediate pressure to make a decision. Making succession a regular part of partner or board meetings can help firms identify potential issues early. It can encourage conversations about who might eventually take on responsibility for key clients, areas of practice and leadership roles.

It also provides an opportunity to consider what the firm needs to do to make itself more transferable and resilient.

Planning early creates options

One of the biggest advantages of early succession planning is choice. If a partner needs to leave the business unexpectedly, there may be a limited number of practical solutions. Clients may need to be moved quickly, colleagues may need to take on additional responsibilities, and the firm may have to make decisions under considerable pressure.

When succession has been considered years in advance, the position can be very different. There may be time to develop internal successors, strengthen management structures, consider a merger or explore an external transfer of the firm’s book of work.

There is no requirement to commit to one particular outcome simply because succession planning has begun. The value is understanding what the options are before they are needed.

Protecting the value of WIP

For many firms, the value of the firm’s WIP can represent an important part of the overall value to be considered as part of succession planning. Yet WIP can be particularly vulnerable during a closure, merger or transfer.

If matters are allowed to drift, clients leave, or files are transferred without proper planning, the value attached to years of work can be significantly reduced.

Early preparation allows the book of work to be reviewed and assessed before decisions are made. Recovery First helps firms understand their WIP and identify opportunities to preserve value when work is transferred to an appropriate receiving firm.

The value attributable to transferred matters can then be apportioned when those matters conclude, with an independent costs lawyer determining the relevant contribution based on the work undertaken.

This creates a structured approach to recognising the value of the outgoing firm’s work rather than simply writing off WIP when the practice closes.

Exploring the Options for Succession or Closure

Planning for succession does not necessarily mean closing the firm. Several routes may be available, depending on the owner’s circumstances and the needs of the practice.

Succession to the next generation – Transferring ownership to existing or incoming partners can provide continuity for clients and employees. A gradual transition can allow the owner to reduce their involvement while younger solicitors take on greater responsibility.

Sale of the practice – Selling the practice to another firm may allow owners to realise value from the business they have built. A strong client base, profitable departments and well-managed WIP may all be relevant to a potential purchaser. Starting early provides time to prepare the practice and explore opportunities.

Merger with another firm – A merger can provide access to greater resources, shared overheads and opportunities for succession, while allowing owners to reduce their involvement over time.

Employee Ownership Trust – For an incorporated law firm that meets the relevant requirements, an Employee Ownership Trust (EOT) can provide an alternative route for owners looking to transfer ownership to the people working in the business. Rather than selling to another law firm or individual purchaser, shares can be transferred to a trust established for the benefit of employees.

Transfer of clients and live matters – Where the business is not being sold as a whole, clients and ongoing matters may be transferred to another practice, subject to client consent and regulatory requirements. This can be particularly relevant for owners who wish to leave but have substantial outstanding WIP.

Orderly Closure – For some, closure will be the most appropriate option. Where there is no suitable successor or purchaser, a planned closure provides time to manage client matters, meet regulatory obligations and recover value from outstanding work.

The best time to plan is before you need to

Succession is often viewed as something that happens at the end of a partner’s career or when a significant change takes place within a firm. It can be much more valuable when treated as an ongoing part of good business management.

Regular conversations at board and partner level can help firms identify future risks, protect client relationships and understand the value within the business.

Recovery First can support law firms that are considering succession and the future of their book of work. By becoming involved at an early stage, it can help firms review and preserve their WIP and consider how client work could be transferred to a panel of suitable receiving firms if required. Find out more about Recovery First and its services here.

About the author

David Johnstone is the founder and Managing Director of Recovery First, an accountancy-led specialist supporting law firms and their professional advisers with succession planning, retirement, restructuring and strategic exits.

An accountant by background, David has spent many years working alongside law firm owners, accountants, insolvency practitioners and legal sector advisers across England and Wales. He is particularly passionate about encouraging law firm owners to consider succession planning well before they intend to retire or step away from their business.

David advocates a “grow it, protect it, pass it on” approach, recognising that effective succession planning should be an ongoing part of running a successful law firm rather than a decision made towards the end of a career. His focus is on helping owners prepare early, preserve the value they have built and understand their options, giving them greater control over the timing and outcome of their eventual exit.

Back to Blogs

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us

Client Testimonial

“Our partnership with Cashroom has been an essential pillar of SP Solicitors. Compliance with the SRA Accounts Rules is not something a firm can get wrong, and knowing our client account is in expert hands means my time goes where it belongs, with my clients.

Cashroom is a true partner, fully integrated into the way the firm runs. They understand how I work and the pace I work at, and they match it. Payments are processed promptly, reconciliations are always in order, and I never have to second guess our compliance position. As the firm grows, I know their support will grow with us. That confidence is worth a great deal.”

Sunny Patel
Sunny Patel
SP Solicitors

Purchase Ledger Management: Keeping Law Firm Finances on Track

For law firms, managing finances involves much more than monitoring client accounts and ensuring bills are paid. There is a constant flow of supplier invoices, staff expenses, subscriptions and other business costs that need to be recorded, checked and paid on time.  This is where purchase ledger management plays an important role. 

A well-maintained purchase ledger helps law firms keep track of what they owe, manage cash flow, VAT returns supplier relationships and maintain accurate financial reports. When it is overlooked or handled inconsistently, unpaid invoices, missed payment deadlines and gaps in financial reporting can quickly create problems for the wider business. 

So, what does purchase ledger management involve, and how can law firms make sure it is working effectively? 

What is a purchase ledger? 

A purchase ledger is a record of the money a business owes to its suppliers. It is also commonly referred to as accounts payable. For a law firm, this could include invoices for IT services, office supplies, professional indemnity insurance, software subscriptions, rent, utilities and external professional services.  

It provides a structured way to record and track these liabilities from the point an invoice is received through to approval and payment. The ledger should also account for credit notes, VAT treatment and payments made, giving the firm a clear picture of outstanding supplier balances. 

Although it primarily covers the firm’s own business expenses, purchase ledger management forms an important part of the wider accounting function. Keeping these records accurate and up to date helps ensure that management accounts reflect the firm’s financial position and supports effective cash flow management. 

Why does purchase ledger management matter for law firms? 

Maintaining control over cash flow 

Knowing what the firm owes, when payments are due and how much cash is available is essential for financial planning. Without an accurate purchase ledger, it can be difficult to establish the value of outstanding liabilities or anticipate upcoming payments. This can make cash flow forecasting less reliable and leave partners with an incomplete picture when making financial decisions.  

A regularly updated ledger gives the firm better visibility of its liabilities and commitments, helping it plan payments around expected income and other expenditure.  

Avoiding missed and duplicate payments 

Supplier invoices can arrive through several channels, including email, online portals and directly from individual departments. Without a consistent approach to recording and checking invoices, there is a risk that something will be overlooked or entered more than once. Missed payments can result in late fees, interrupted services or unnecessary follow-up from suppliers. Duplicated payments can tie up cash and create additional work for the finance team when they need to be identified and recovered. 

A clear purchase ledger process helps ensure invoices are recorded correctly, checked against supporting information and reviewed before payment.  

Supporting accurate management accounts 

Partners and practice managers rely on management accounts to understand how the firm is performing. However, these figures are only useful when the underlying financial information is complete and accurate. If supplier invoices have not been recorded, expenses may be understated and the firm’s reported profitability may not reflect its actual position. Similarly, an inaccurate record of outstanding liabilities can affect cash flow forecasts and financial planning. 

Accurate nominal coding is also important to ensure expenditure is recorded in the correct category. For example, a supplier that primarily sells stationery may also supply office furniture. Although both purchases come from the same supplier, they should generally be allocated to different nominal codes because they represent different types of expenditure. Stationery would typically be recorded under office supplies or stationery, while office furniture may be recorded under furniture and equipment. Depending on the firm’s accounting policy, the value of the furniture and its expected useful life, it may need to be treated as a fixed asset rather than an everyday expense. 

Recording costs correctly allows the firm to see how much it is spending in each area, monitor budgets and distinguish routine running costs from larger investments. If everything purchased from a supplier is allocated to the same nominal code, management accounts may not provide an accurate breakdown of expenditure, making it harder to identify trends and make informed financial decisions. 

Keeping the purchase ledger up to date and ensuring invoices are coded correctly supports more reliable reporting and gives decision-makers greater confidence in the figures they are reviewing. 

Ensuring VAT is accurate 

Supplier invoices provide the supporting information needed to identify eligible input VAT and ensure figures are reported correctly. However, the VAT treatment is not determined solely by the supplier, but by the goods or services being supplied and the VAT rules that apply to that transaction. Even when a supplier charges VAT on an invoice, the law firm should check that the treatment is correct before recording it. 

If invoices are missing, recorded against the wrong amounts or allocated to the wrong VAT codes, this can lead to errors in VAT calculations and additional work to correct them. In some cases, firms may miss eligible VAT recovery or reclaim VAT without the appropriate supporting evidence. 

Keeping the purchase ledger up to date, checking VAT treatment carefully and using the correct VAT codes helps law firms maintain accurate VAT records and meet their reporting obligations. It also makes it easier to locate supporting documentation if a query arises or records need to be reviewed. 

Keeping supplier relationships on track 

Law firms depend on a range of suppliers to operate effectively, from legal software providers to IT support companies and professional advisers. Paying invoices in accordance with agreed terms helps maintain good working relationships and reduces the time spent responding to payment queries. It can also help the firm avoid unnecessary disputes and protect access to important services.  

A reliable purchase ledger function makes it easier to identify upcoming payments and deal with queries before they become larger issues. 

What does effective purchase ledger management involve? 

A good purchase ledger process should provide clear oversight from the moment an invoice arrives to the point it is paid and reconciled. 

Key activities include: 

  • Entering supplier invoices into the accounting system with the correct supplier details, dates, amounts and nominal codes. 
  • Confirming that charges are valid, accurate and authorised by the appropriate person before payment. 
  • Reviewing outstanding invoices and planning payments in line with agreed terms and the firm’s cash flow. 
  • Checking ledger balances against supplier statements to identify missing invoices, unallocated payments or discrepancies. 
  • Keeping supporting documentation and a clear audit trail of invoices, approvals and payments. 
  • Providing visibility of amounts owed and upcoming commitments to support cash flow management and financial reporting. 

These activities may appear straightforward individually, but they require consistency and attention to detail, particularly in firms with high transaction volumes or several offices and departments. 

Common purchase ledger challenges for law firms 

Even firms with established accounting systems can encounter difficulties managing their purchase ledger. 

Limited staff capacity 

Purchase ledger management can be time-consuming. When finance teams are balancing supplier invoices alongside payroll, reconciliations, client account duties and month-end reporting, routine tasks may fall behind. 

Reliance on manual processes 

Invoices received by email, approvals handled through separate systems and information entered manually can create duplication and increase the likelihood of errors. Where practical, using integrated systems and clear approval workflows can reduce unnecessary administration. 

A lack of visibility 

If invoices are held in inboxes or awaiting approval with individual staff members, it can be difficult to establish the firm’s complete outstanding liabilities. This makes it harder to identify bottlenecks and plan payments effectively. 

Inconsistent procedures 

Without clear responsibilities and approval limits, invoices may be processed differently across teams. This can make oversight more difficult and increase the risk of unauthorised or incorrectly recorded expenditure. 

Recognising these challenges is the first step towards improving the way purchase ledger activities are managed. 

Could outsourcing purchase ledger management help? 

For some law firms, outsourcing elements of their finance function can provide additional capacity and a more consistent approach to routine accounting tasks. Cashroom can support purchase ledger activities, helping with invoice processing, supplier reconciliations, payment scheduling and the maintenance of accurate financial records, depending on the agreed service. This reduces the administrative burden on internal staff and helps firm’s keep financial information up to date without having to manage every task in-house. 

We’ve seen law firms of all sizes and at different stages benefit from outsourcing, whether they’re looking to free up internal resources, manage periods of change or give partners and senior managers greater visibility of their financial position. The right arrangement should fit the firm’s existing systems, responsibilities and approval procedures. Clear controls must remain in place, including appropriate authorisation of payments and oversight of expenditure. 

Keeping your firm’s finances in good order 

Purchase ledger management may not always receive the same attention as client accounting or financial reporting, but it does play an important role in keeping a law firm’s finances organised. Accurate records, timely invoice processing, clear approval procedures and regular reconciliations all contribute to better cash flow visibility, more reliable management accounts and stronger supplier relationships. 

For firms finding it difficult to keep on top of these responsibilities, reviewing the current process can highlight opportunities to improve efficiency and strengthen financial oversight. At Cashroom, we support law firms with their wider finance and accounting requirements, helping them manage the financial responsibilities that sit behind the day-to-day running of the practice. 

If your firm would benefit from additional support with its finance function, get in touch to discuss your requirements.

Want to know more?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs

Client Testimonial

“Our partnership with Cashroom has been an essential pillar of SP Solicitors. Compliance with the SRA Accounts Rules is not something a firm can get wrong and knowing our client account is in expert hands means my time goes where it belongs, with my clients.

Cashroom is a true partner, fully integrated into the way the firm runs. They understand how I work and the pace I work at, and they match it. Payments are processed promptly, reconciliations are always in order, and I never have to second guess our compliance position. As the firm grows, I know their support will grow with us. That confidence is worth a great deal.”

SP Solicitors


Keeping Your Law Firm’s Finances from Going Up in Smoke

Bonfire Night is a time for fireworks, sparklers and spectacular displays. But when it comes to your law firm’s finances, “going up in smoke” is something you want to avoid.

Most finance problems do not appear overnight. They often start with something small. A process takes a little longer than it should. A spreadsheet is created to work around a limitation in a system. A reconciliation is delayed because the finance team is dealing with more urgent work. A report takes days to pull together because the information sits across different systems. Individually, these issues may not seem significant. Over time, however, they can add pressure to your finance team, increase the risk of errors and make it harder for partners and management to get a clear picture of the firm’s financial position.

A closer look at your finance function could reveal where time, resources and efficiency are being lost.

When your finance team is burning the candle at both ends

A busy finance team can often keep things moving, even when resources are stretched. Payments are processed, reconciliations are completed and month-end reports eventually make their way to the partners. The problem is what happens in between.

Imagine a finance manager spending the first few days of every month chasing information from different departments, checking spreadsheets, resolving discrepancies and preparing reports. By the time the information is ready, they are already thinking about the next deadline. The work is getting done, but the process is consuming more time than it should. This can become particularly challenging when a member of the finance team is on holiday or off sick. If only one person knows how a particular process works, even a short absence can leave a significant gap.

For firms facing this kind of pressure, outsourcing some or all of the finance function can provide additional capacity. Cashroom’s team of legal finance specialists can support firms with day-to-day legal cashiering tasks, allowing internal teams to focus their time where it is most needed.

Don’t let manual processes spark problems

Manual processes are common in law firms. Sometimes they are necessary, but sometimes they remain because “that is how we have always done it”. For example, a firm might export information from its practice management system, manipulate it in Excel, manually check the figures and then enter information into another system. While this might work, every additional manual step creates another opportunity for something to go wrong. A payment could be entered incorrectly. A figure could be copied into the wrong spreadsheet. A reconciliation could take considerably longer because someone has to investigate a discrepancy between two sets of records. None of these problems necessarily creates a crisis. But they add friction to the finance function and increase the amount of time spent checking and correcting work.

Technology and integration like The Cashroom Portal, can help reduce this reliance on manual processes, particularly where financial information can move between systems automatically.

When compliance starts to create pressure

Legal finance comes with responsibilities that cannot be overlooked. Client money, reconciliations, transactions and financial records all need to be handled appropriately, with processes that support the firm’s regulatory obligations.

Consider a firm where the finance team is under significant pressure. A routine reconciliation takes longer than expected because several transactions need investigating. At the same time, the team is dealing with payments, billing queries and month-end reporting. When resources are stretched, there is a risk that important compliance-related tasks become another source of pressure. Compliance works best when processes are clear, the right checks are in place and the people handling the work have the appropriate knowledge and experience.

For law firms, having experienced legal finance professionals involved can provide valuable reassurance that financial processes are being managed with the regulatory environment in mind.

What’s burning through your partners’ time?

Not every finance issue sits within the finance department. Poor financial processes can create work for partners and fee earners too. For example, a partner might need to chase an outstanding invoice because there is no effective credit control process. A fee earner might contact the finance team several times because they cannot easily see the status of a transaction. A managing partner might wait for management accounts because the information takes too long to compile. Each interruption might only take a few minutes, but across an entire firm, those minutes can quickly add up.

Partners should have access to the financial information they need to make decisions, without becoming involved in routine finance administration. A well-supported finance function can help keep those responsibilities in the right place.

Don’t let your financial visibility disappear in a cloud of smoke

Good financial information is only useful if it is available when the firm needs it. Management accounts can help partners understand revenue, costs, profitability, cash flow and performance across different areas of the business. But if producing those reports is a lengthy manual exercise, they may arrive too late to influence decisions.

For example, if a department’s costs have increased significantly over several months, the firm needs to know sooner rather than later. Waiting until year-end to identify the issue leaves fewer opportunities to address it. Accurate and timely reporting gives law firm leaders a clearer view of what is happening financially and where attention may be needed.

For firms looking for better visibility, Cashroom’s management accounts service provides regular financial information to help partners and management understand performance and make informed decisions.

Is your technology helping or hindering?

Most law firms rely on technology to support their financial and operational processes. But having the right systems in place is only part of the picture. They also need to work together effectively and be used to their full potential.

A firm might have invested in a practice management system, accounting software and other financial tools, but still find that information does not flow smoothly between them. This can leave staff switching between systems, checking information manually or finding workarounds when a process does not work as expected.

If information held in a practice management system does not feed through to the relevant financial processes, the finance team may spend unnecessary time checking and transferring information. The technology is there, but the firm is not getting the full benefit from it. This does not necessarily mean replacing existing software. Better configuration, integration or training may be enough to improve how systems work together and reduce unnecessary administration.

Keep the fireworks for Bonfire Night

There is nothing wrong with a little excitement on Bonfire Night, however, your law firm’s finance function should be predictable, well organised and under control. If small finance issues are starting to take up more time, create unnecessary pressure or make it harder to get the information you need, it may be time to take a closer look.

After all, the only thing that should be going up in smoke this November is a firework.

Cashroom provides outsourced legal finance services to law firms, including legal cashiering, management accounts, payroll, credit control, statutory accounts and tax returns.

Want to know more?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs

Client Testimonial

“Our partnership with Cashroom has been an essential pillar of SP Solicitors. Compliance with the SRA Accounts Rules is not something a firm can get wrong and knowing our client account is in expert hands means my time goes where it belongs, with my clients.

Cashroom is a true partner, fully integrated into the way the firm runs. They understand how I work and the pace I work at, and they match it. Payments are processed promptly, reconciliations are always in order, and I never have to second guess our compliance position. As the firm grows, I know their support will grow with us. That confidence is worth a great deal.”

SP Solicitors


Don’t Let Unpaid Invoices Haunt Your Law Firm

Halloween is the season for spooky stories, unexpected scares and things that go bump in the night. But for law firms, few things are more unsettling than a growing list of unpaid invoices and clients who are slow to pay. 

Credit control is an important part of maintaining a healthy law firm, yet it can easily slip down the priority list when teams are busy managing client accounts, payroll and the many other demands of running a practice. Without regular attention, outstanding fees can accumulate, putting pressure on cash flow and making financial planning more difficult. 

A consistent approach to credit control can help firms stay on top of their debtors, identify potential problems earlier and reduce the risk of unpaid fees becoming a much bigger concern. 

The Fright of Unpaid Invoices 

Late payments can affect more than a firm’s bank balance. When fees remain outstanding, firms may find it harder to plan for upcoming expenses, manage working capital and make informed decisions about future investment. The challenge is that overdue invoices can build up gradually. A handful of late payments might not seem particularly concerning, but when several clients fall behind, the total amount owed can become significant. 

Monitoring outstanding invoices regularly helps firms understand how much money is owed, identify overdue accounts and decide where follow-up is needed most. 

Skeletons in the Debtors Ledger

A debtor’s ledger can reveal a great deal about a firm’s financial position, but only if it is reviewed regularly and acted upon. Looking at the age of outstanding invoices helps firms identify debts that need attention. An invoice that is a few days overdue may require a routine reminder, while an older balance could need a more direct conversation or further investigation. 

It is also worth looking for patterns. Are certain clients regularly late with payments? Are invoices being disputed? Are reminders being sent promptly? Understanding why payments are delayed can help firms address recurring issues rather than continually reacting to them. 

Don’t Let Debtors Come Back to Haunt You

Effective credit control starts before an invoice becomes overdue. Clear payment terms, accurate billing and good communication can help establish expectations from the outset. 

Once an invoice has been issued, firms should have a clear routine for following up unpaid fees. This might include reminders before and after the due date, regular reviews of outstanding balances and a process for escalating accounts that remain unpaid. 

Consistency matters. If follow-ups are delayed whenever the team becomes busy, clients may not treat payment deadlines as a priority. Keeping accurate records of reminders, conversations and agreed payment dates also helps ensure that nothing is overlooked. Where a payment is disputed or a client is experiencing difficulties, early communication can help establish the reason and determine the appropriate next steps. 

A Credit Control Horror Story 

For many firms, the biggest challenge is finding the time to maintain consistent credit control alongside everything else their finance team needs to do. Legal finance teams already have a range of responsibilities, from client account work and reconciliations to payroll and reporting. When resources are stretched or a key member of staff is absent, chasing outstanding invoices can quickly fall behind. This can create a cycle in which overdue debts receive attention only when cash flow becomes a concern. By then, some balances may be considerably older and more difficult to collect. 

Reviewing workloads, setting aside dedicated time for credit control and establishing clear responsibility for follow-ups can help. For firms that need additional capacity, outsourcing credit control can also provide support without requiring them to expand their internal team. 

Take the Fear Out of Credit Control 

Unpaid invoices do not have to become a recurring nightmare. With clear payment terms, regular debtor reviews and consistent follow-ups, law firms can maintain better oversight of the money owed to them. At Cashroom, we support law firms with credit control alongside our wider legal finance services. Our team can help chase outstanding invoices and keep debtor information up to date, giving firms additional support in managing their finances. 

Keeping on top of outstanding fees takes time and consistency, but addressing debts early can help firms maintain a clearer picture of their financial position and avoid unnecessary scares long after Halloween is over. 

Contact us

Looking for ways to improve your law firm’s cash flow?

Our guide 10 Simple Ways to Manage Your Law Firm’s Cash Flow, shares practical steps to help your firm manage it’s finances and plan for the months ahead.

Read the guide
Back to Blogs

Client Testimonial

We have been working with The Cashroom for the past eight years and it has been a fantastic relationship throughout. We use Cashroom for their expertise in legal cashiering, management accounts, payroll and VAT returns, and consistently receive a reliable, high quality service. Their team works brilliantly alongside our in-house team and delivers a secure, efficient and compliant finance function that supports our business as it continues to grow. Their flexible services, combined with a genuine personal touch, mean we have a finance function that fits our needs perfectly. Their processes work particularly well for our busy conveyancing team, helping us operate efficiently while maintaining the high standards our clients expect.


Meet our Head of Onboarding

For Katie Wilson, a career in legal finance has been built through years of experience supporting law firms. Katie joined Cashroom in 2015 and has held several roles across the business. She is now Head of Onboarding, where she leads the transition of new clients to Cashroom services.  

Her role extends beyond onboarding. Katie also manages client projects, process design and efficiency improvements, supporting firms with everything from financial migrations and system changes to resolving account issues and clearing backlogs.  With extensive experience of legal accounting, multiple practice management and accounting systems, banking platforms and the SRA and CLC Accounts Rules, Katie brings a practical understanding of the challenges law firms face when managing their finance functions. 

 Q. How did you come to join Cashroom, and how has your role developed since then?

A. I had spent more than 15 years working in-house as a Legal Cashier and Senior Legal Cashier within a couple of large law firms, when I was approached by a former colleague who had recently joined Cashroom and asked if I would be interested in a new challenge.

After learning more about Cashroom and the opportunities the role could offer, it was an easy decision. The initial learning curve was steep, but I relished the challenge and quickly became invested in Cashroom’s vision and wanted to take on more responsibility. 

Within a couple of months, I moved into the role of Onboarding Manager, where I was able to use the experience, I had built throughout my legal cashiering career to develop and improve processes. 

As Cashroom continued to grow, so did my knowledge and experience. I progressed into senior management and became Head of Onboarding, a role that continues to challenge me and give me the opportunity to work with a wide range of law firms.

Q. How does building a strong relationship with a client help during the onboarding process

A. When onboarding a new client, it is important to put them at ease and make the transition to Cashroom as smooth as possible. For some clients, this can be their first experience with outsourcing, so it is important to understand their concerns, explain how the process will work and show them the benefits of having access to a wider pool of legal accounting experience.

Personally, this is one of my favourite parts of the role. I enjoy talking to clients about their requirements and working with them to agree the right approach to support their business. Building that relationship from the outset helps us understand what the client needs and gives us a strong foundation for the relationship going forward. 

Q. How does your experience help when providing advice and support to law firms joining Cashroom?

A. Recently, we have seen an increase in enquiries from law firms that have experienced issues with their previous finance arrangements, including poor accounts or record keeping, or firms looking to migrate to a new accounting or practice management platform.

Our experience over many years means we can provide specialist advice and practical support to help address these challenges. This can include identifying issues with existing processes, supporting system migrations and helping firms establish effective ways of working from the outset. 

Our clients benefit from the depth of experience we have built across Cashroom, with hundreds of legal accounting professionals, experience communicating with regulators, knowledge of more than 40 accounting systems and experience working with a wide range of banking platforms. 

That breadth of experience means we can often draw on knowledge from across the business to help find the right approach for each client. 

Q. What is your favourite aspect of the job?

A. Helping our clients find a better way! I really enjoy discussing their needs and looking at how we can help them. I’m naturally driven by finding ways to make things more efficient and straightforward.

For me, it’s about making sure our clients have the best and most user-friendly experience possible, while ensuring the way we work is tailored to their individual business. 

Q. What are some of the challenges involved in helping law firms change the way they manage their finance function

A. One of the biggest challenges can be supporting clients through change. People can naturally be cautious about changing processes they are familiar with, even when there are clear benefits to doing things differently. Part of my role is helping clients understand the changes we are proposing, communicating how we will support their staff through the transition and showing how the changes can benefit the firm and its staff.

Ultimately, it is about making sure the changes we introduce improve the client experience, strengthen regulatory compliance and make their finance operations more efficient. 

Katie’s role highlights the importance of getting the transition to outsourced finance right from the beginning. By combining her legal cashiering experience with her knowledge of processes, systems and change management, she helps law firms navigate the move to Cashroom and find ways of working that suit their individual needs. 

For Katie, the focus remains simple: understanding what each client needs and finding a better way to support them.  

Katie WilsonKatie Wilson

Head of Onboarding at Cashroom

Back to Blogs

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us

Client Testimonial

We have been working with The Cashroom for the past eight years and it has been a fantastic relationship throughout. We use Cashroom for their expertise in legal cashiering, management accounts, payroll and VAT returns, and consistently receive a reliable, high quality service. Their team works brilliantly alongside our in-house team and delivers a secure, efficient and compliant finance function that supports our business as it continues to grow. Their flexible services, combined with a genuine personal touch, mean we have a finance function that fits our needs perfectly. Their processes work particularly well for our busy conveyancing team, helping us operate efficiently while maintaining the high standards our clients expect.


How Stepping Beyond My Formal Role Shaped My Career

In 1993 when I qualified as a solicitor the career that lay ahead of me was simple and straightforward. I was lucky enough to qualify with a great old firm (Slater Heelis) and then to move to a fantastic firm with big ambition (Hill Dickinson), followed by a dynamic personal injury firm (Silverbeck Rymer). 

I had made it to salaried partner and thought I was set. Work hard, build happy client base and progress to equity. That’s just what always happened. 

But… 

The insurance and personal injury sector in the late 1990s were about to undergo a seismic shift. I’ve always felt it was most likely because the insurers realised the fastest way for them to save money was not on plaintiff (claimant) damages, nor on plaintiff’s legal fees. 

It was on their own (defendant) legal fees. 

A salaried partner was about the worst position to be in. Expensive. The job could be done by someone more junior really. 

I decided I needed to find a different way of earning. 

By this time, almost by osmosis, I’d started to develop transferable skills- BD, Teamwork, Process management, Networking. In the early 2000s myself and a colleague founded a recruitment business, building on the network of connections, and developing management, leadership and some tech skills. 

The recession in 2008 took me in another direction and I moved to a huge global IT business – helping them to design a strategy to break into the legal sector and then delivering sales and BD for them. My networking, presentation and strategic relationship skills grew. I gained world class insight into issues around process optimisation and cyber threats which I was then able to bring into my legal sector engagements. 

I’d travelled a long way from my original role as a solicitor, and I had gathered skills that weren’t in any way part of my ‘formal’ career as a lawyer- networking, strategic thinking, karma marketing, process, tech, conference presentation. 

When the opportunity to join Cashroom arose 13 years ago, I found I had (like Liam Neeson) a unique set of skills, and ones which fitted wonderfully with my new role. 

So what’s the lesson here? 

I suppose it’s that the skills lawyers develop can be powerful- they include analytical thinking, professionalism, discipline. Those skills are valuable and continue to have relevance every day for me. The skills I’ve developed outside the law firms are now an augmentation to that base layer, and from what I see in the market, many of those attributes remain worthwhile whether you’re a lawyer or a supplier. 

So, the message for lawyers and indeed anyone within the legal sector- be bold, be inquisitive and learn new skills. It’s exciting, and it can take you to some wonderful and unforeseen places. 

About the author

Alex Holt, Chief Revenue Officer at The Cashroom, has over 30 years’ experience in the legal sector, including as a law firm partner. He brings deep expertise in law firm operations, financial management, and strategic growth, helping firms optimise processes, improve efficiency, and navigate change while delivering exceptional client service.

Back to Blogs

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us

Client Testimonial

We have been working with The Cashroom for the past eight years and it has been a fantastic relationship throughout. We use Cashroom for their expertise in legal cashiering, management accounts, payroll and VAT returns, and consistently receive a reliable, high quality service. Their team works brilliantly alongside our in-house team and delivers a secure, efficient and compliant finance function that supports our business as it continues to grow. Their flexible services, combined with a genuine personal touch, mean we have a finance function that fits our needs perfectly. Their processes work particularly well for our busy conveyancing team, helping us operate efficiently while maintaining the high standards our clients expect.


What’s holding your firm back from better business development?

Guest blogger: Joanna Gaudoin

I see it frequently in many firms: very few people are contributing meaningfully to business development. I always find it interesting that lawyers are typically risk-averse, yet they run tremendous risk when it comes to BD.

Firms always hope it won’t happen to them, but in reality, people become unwell and people leave. That’s the negative perspective; the positive is to think about all the additional opportunities that can be created when you’ve got more people contributing to business development.

There are many reasons why most firms don’t have the majority of lawyers contributing. I’m going to go through five of them and suggest action you can take to deal with them.

The top 5 reasons lawyers struggle with BD

1. Lack of leadership focus on BD being important

How to tackle: If your firm wants to grow, ensure there is partner buy-in to this vision and what that means in terms of behaviour and action. Getting different results means taking different action. The leadership of the firm need to not only role model good BD behaviours but also encourage and support others to engage through time and incentivisation.

2. Lawyers don’t understand why they need to do it, especially as it isn’t part of qualifying

How to tackle:

a) Get them to consider the services they buy and how important it is to know, like and trust the person who will be doing the work for them. Legal services are often an emotive as well as rational purchase, even when they are on behalf of a company. Therefore, potential clients want to feel valued by the people involved in their work and trust that there will be ease of working together and strong communication. It’s about more than technical expertise.

b) Ideally, your firm would have a team approach to BD by department. This means a BD strategy and activity plan where everyone has a role to play in the fundamentals of building their profile and network, as well as specific tasks that contribute to overall BD activity.

c) Even juniors can support senior lawyers to make some BD activities happen, such as researching other professional services people the senior lawyers should meet to build relationships and develop introduction opportunities.

3. Don’t know what to do

How to tackle: BD can feel like a nebulous topic for many lawyers. Therefore, it is vital to consider which services you want to focus on delivering for clients, as this informs the BD activity plan that the team puts together. This then provides clarity on the specific BD activities that need to take place. For most, there will be some granular tasks to implement to support the overall activity.

4. Don’t know how

How to tackle: If an individual has responsibility for an overall BD activity or even a granular task, check that they have the know-how and skills to do it well. A simple example is individuals only going to networking events if they have the skills and confidence to navigate the room and build relationships that may lead to opportunities over time.

5. Lack of accountability

How to tackle: Ensure individuals are accountable for specific elements of the BD plan and that there is both a timeline and specific review points so progress can be assessed. Without accountability, BD will always go to the bottom of the list. BD should also be a key part of performance reviews.

What about your firm?

What is the main sticking point in your firm? Is it one of these or something else?

Understanding what is standing in the way of business development being done by more people, more effectively, to achieve better outcomes is an important consideration. Firms need to understand the barriers and have an approach in place that delivers positive outcomes in both the short and long term.

If you’d like to explore how to break down the barriers to achieve better business development outcomes, contact me to arrange a conversation.

If you’d like to receive a 5-minute read on Business Development Insights, you can request it here.

About the author

Joanna Gaudoin helps law firms and their people take a structured and skilled approach to business development. Many professionals find winning and retaining challenging, yet it’s a core part of their role. Joanna helps individuals and firms build clarity, confidence, and capability to develop and retain valuable client relationships.
Through her company, ClientWise, Joanna works to reduce over-reliance on a few individuals bringing in work and supports a more consistent, embedded approach to growth. Her work spans consultancy, facilitation, and training through firm-wide programmes, targeted workshops, and individual coaching. Her proven framework, The 5 Ps of Business Development©, underpins all her work. Joanna has 15+ years of experience with law firms, accountants, banks, and other professional services. She previously worked in brand marketing and consultancy. She’s an experienced and engaging speaker and author of Getting On: Making work work, and co-author of Globe Law and Business titles, Business Development for Women Lawyers and Essential Reads for the Modern Lawyer.

Back to Blogs

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us

Client Testimonial

“Our partnership with Cashroom has been an essential pillar of SP Solicitors. Compliance with the SRA Accounts Rules is not something a firm can get wrong, and knowing our client account is in expert hands means my time goes where it belongs, with my clients.

Cashroom is a true partner, fully integrated into the way the firm runs. They understand how I work and the pace I work at, and they match it. Payments are processed promptly, reconciliations are always in order, and I never have to second guess our compliance position. As the firm grows, I know their support will grow with us. That confidence is worth a great deal.”

Sunny Patel
Sunny Patel
SP Solicitors

Is Your Law Firm’s Financial Compliance Really Working?

For law firms, financial compliance is something that needs attention every day. Client money must be handled correctly. Reconciliations need to be completed accurately and on time. Payments require appropriate checks and approvals. Records need to be maintained, and everyone involved in the process needs to understand their responsibilities. 

With so many demands on a law firm, it can be easy for compliance processes to become something that happens in the background rather than something that is actively reviewed. The question is: how confident are you that your financial processes are working as they should? 

Compliance is more than a policy 

Having a compliance policy in place is important, but the real test is how those policies work in practice. For example, a firm may have a documented procedure stating that all client account payments must be independently checked before they are authorised. On paper, the control is there. But if the person carrying out the check is unclear about what they are expected to verify, or the process is regularly bypassed when the team is busy, the policy offers little protection. Good compliance comes from making sure the right controls are built into everyday processes and are practical for staff to follow consistently. 

A firm may have documented procedures for dealing with client money, but are those procedures consistently followed? Are reconciliations completed within the required timescales? Are payments subject to appropriate checks? Is there a clear audit trail? Do staff know what to do when something does not look right? These everyday processes form the foundation of financial compliance. 

Where can financial compliance go wrong? 

There are several areas that deserve particular attention. 

  1. Client account reconciliations

Regular and accurate reconciliations are fundamental to effective client account management. They provide an opportunity to identify discrepancies, investigate unusual transactions and make sure the firm’s records agree with the relevant bank accounts. A reconciliation should not simply be viewed as another task to complete. It is an important control that gives the firm visibility over client money. 

  1. Payment approvals

Payments are another area where strong controls matter. Firms should have clear processes around who can request, check and authorise payments. The appropriate level of approval should be clear, particularly for higher-value or unusual transactions. 

Technology can also support these controls by creating structured approval workflows and clear audit trails, helping firms reduce the reliance on informal processes and email communication. 

  1. Record keeping and audit trails

If a firm needs to demonstrate how a transaction was processed, can it easily show what happened? A strong audit trail should provide visibility over requests, approvals, transactions and relevant communications.  

Good record keeping supports regulatory compliance, but it also makes internal reviews and inspections much easier. 

  1. Segregation of client and office funds

Maintaining the appropriate separation between client and office money is a fundamental responsibility for law firms. Processes should make this distinction clear and provide sufficient controls to prevent funds from being incorrectly transferred or recorded. This is an area where well-designed systems and consistent procedures can help reduce the risk of human error. 

  1. Staff knowledge and training

Even the best processes can fail if the people responsible for carrying them out do not understand them. Compliance responsibilities should be clear across the team, with appropriate training and support to make sure staff understand the firm’s procedures and their role within them. Training should also be kept up to date as regulatory requirements and internal processes change. 

Don’t wait for an inspection to find the gaps 

One of the most useful ways to assess your firm’s financial compliance is to review your processes before you are required to demonstrate them. A proactive review can highlight: 

  • Processes that rely too heavily on manual intervention 
  • Inconsistent approaches between members of staff 
  • Gaps in approval procedures 
  • Reconciliation issues 
  • Incomplete or difficult-to-follow audit trails 
  • Areas where responsibilities are unclear 
  • Processes that have not been reviewed for some time 

Identifying these issues early gives firms the opportunity to address them before they become a bigger problem. It can also make regulatory inspections and internal audits considerably less stressful. 

Technology can strengthen compliance 

Technology cannot replace good processes or experienced people, but it can provide another layer of control. For example, automated workflows, secure communication, audit trails, real-time reporting and payment verification can help firms reduce manual errors and improve visibility over financial activity. 

The Cashroom Portal is designed specifically around the financial requirements of law firms, providing features including approval workflows, audit trails, Open Banking and Confirmation of Payee checks. The aim is to make compliant processes easier to follow as part of everyday work, rather than relying on additional checks at the end of the process. 

Take a closer look at your own processes 

Compliance should be an ongoing process rather than a once-a-year exercise. Taking time to review how your firm’s financial processes actually work can help identify risks, improve consistency and give partners and senior teams greater confidence in the way client money is being managed. 

To help you get started, Cashroom has created a Legal Compliance Checklist for Law Firms. The practical guide covers key areas including client account reconciliations, audit documentation, segregation of funds, approval workflows, internal controls, risk monitoring and staff training. It can be used as part of an internal review, for audit preparation or as a useful discussion tool with your finance team. 

Compliance starts with the everyday 

Strong financial compliance is built into the way a firm operates every day. When responsibilities are clear, processes are consistent, controls are effective and the right technology is in place, compliance becomes part of the workflow rather than an additional burden. For law firms, that can mean greater confidence in the management of client money, better visibility over financial processes and fewer avoidable risks. 

The question isn’t whether your firm has compliance processes in place. It’s whether those processes are working as effectively as they could be. 

Take a proactive approach to client account compliance

Download the Legal Compliance Checklist for Law Firms and see how your firm’s current processes meassure up.

Download the guide
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

Meet Our Chief Operations Officer: Steven O’Day

As Chief Operations Officer at Cashroom, Steven O’Day plays a key role in shaping how we deliver our services, support our clients and continue to innovate. From leading operational strategy to helping develop our award-winning technology, Steven’s experience has been instrumental in Cashroom’s growth while ensuring we maintain the high standards our clients expect. 

Although Steven officially joined Cashroom in 2020, his involvement with the business began much earlier. 

“I’d been helping Cashroom since 2012, initially with website updates, office setup and some process design as the business was growing. At the time, I was working in banking technology, designing secure and resilient platforms and using that knowledge to help Cashroom. I’d always been involved behind the scenes.” 

From an idea to the Cashroom Portal 

As Cashroom grew, conversations naturally turned to how technology could improve its processes and the experience it provided to clients. 

Steven and Paul O’Day, now Cashroom’s Chief Technology Officer, had been developing software as a side project. They adapted this technology to create an early prototype of what would become the Cashroom Portal, initially with the aim of reducing the business’s reliance on email. 

After presenting the prototype to Cashroom’s leadership team in 2015 and receiving positive feedback, they continued to develop the platform in close collaboration with the operational teams. This ensured the technology reflected not only how Cashroom worked, but also what its clients needed. 

“It wasn’t about building technology for the sake of it. We worked closely with the people using it every day to make sure it genuinely improved the service we provide.” 

Today, the Cashroom Portal supports hundreds of law firms every day and continues to evolve alongside the legal sector. 

“I’m incredibly proud of what we’ve built. The platform has always been designed to be secure, resilient and scalable, but we’re constantly looking at ways to improve it.” 

Looking ahead, Steven sees further integration with practice management systems, banks and other legal technology providers as an important part of making legal finance simpler and more efficient. 

“Our aim is to create a more connected experience, reducing manual processes while maintaining the controls that law firms need.” 

Building strong foundations for growth 

Steven joined Cashroom full-time as Head of IT in 2020. His responsibilities quickly expanded beyond technology to include compliance, risk, project management and HR, ultimately covering the breadth of Cashroom’s internal operations. 

As the business continued to grow, Steven stepped into the role of Chief Operations Officer, bringing his experience of managing operations at scale to support Cashroom’s people, processes and technology. 

“My focus has always been on building strong foundations for growth. That means having the right people, efficient processes and the right technology in place to support both our team and our clients.” 

Over the past few years, Steven has worked closely with Cashroom’s senior management team to strengthen operational processes, improve collaboration across departments and introduce best practices that help the business maintain consistently high standards as it grows. 

Supporting Cashroom’s next chapter 

With Cashroom continuing to expand across the UK and the US, Steven is excited about what comes next. 

“We’re continuing to invest in our technology, enhance our processes and expand the services we offer. As we grow, it’s important that we continue to deliver the same high level of service our clients expect while creating opportunities for our people to develop their careers.” 
For Steven, the future of legal finance lies in combining innovative technology with specialist expertise. By making processes more connected and efficient without compromising security, resilience or control, Cashroom can help more law firms build stronger finance functions. 

“There’s a huge opportunity to continue improving how legal finance is delivered. By listening to our clients and continually refining what we do, we can keep developing solutions that make a real difference to law firms.” 

Need Support with Legal Accounting?

Cashroom specialises in outsourced accounting services for law firms across the UK, helping firms stay compliant, efficient and financially informed.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

Partner Retirement: A Business-Critical Issue For Firms

Guest bloggers: Sarah Harrison & Graeme Menzies 

Partner retirement is often treated as a personal milestone: a conversation about when someone wants to leave, followed by a handover and a few farewell drinks.

For partner-led firms, that approach can be dangerously simplistic, given that a partner’s retirement is business-critical in many ways. The firm may be dealing with the loss of a major client relationship-holder, decades of institutional knowledge, leadership experience, revenue and influence. At the same time, the individual is navigating a profound personal transition involving identity, status, purpose, relationships and life beyond partnership.

Client relationships need to be transitioned, not simply transferred

A client relationship cannot simply be handed from one partner to another.

If a client has worked with the same partner for 20 years, trust needs time to develop with their successor. A handover document or an introduction shortly before retirement is unlikely to be enough.

Good succession planning starts early, giving the retiring partner and successor time to work alongside each other, introduce each other to key contacts and gradually establish the successor as the client’s trusted adviser.

This is particularly important for SME firms, where a relatively small number of clients may represent a significant proportion of revenue.

The same applies to knowledge. A spreadsheet can record information, but it cannot replicate decades of judgement, relationships and context. Effective transition requires time for conversations, mentoring and shared experience while the retiring partner remains fully engaged.

Succession should create opportunity

Retirement can also be an opportunity for the next generation.

A well-planned transition can open up leadership roles, client relationships and equity opportunities for other partners and senior lawyers. It can help ambitious people see a future for themselves within the firm.

If retirement is left until the final year, however, succession can become a scramble to fill a gap rather than a considered investment in the firm’s future.

The human side is a business issue too

For someone who has spent three decades building a legal career, partnership may provide far more than an income. It can provide identity, status, intellectual challenge, routine, social connection and a strong sense of purpose.

So asking someone simply, “When do you want to retire?” can be a surprisingly significant question.

What happens afterwards? Who will they be when they are no longer a partner? Do they want to stop working altogether, or use their experience differently? Where will they find purpose, stimulation and connection?

These are personal questions, but they can have business consequences.

Retirement should therefore be treated not simply as an HR issue, but as a strategic business issue — and a wellbeing issue for the individual.

A partner who feels anxious, undervalued or uncertain about the future may find it harder to engage positively with succession. They may hold onto client relationships because letting go feels like losing part of their identity, or delay decisions because they are not emotionally ready to leave.

A partner who has had time and support to think about what comes next is more likely to approach the transition with confidence and generosity.

The power of specialist retirement coaching

This is where specialist retirement coaching can be particularly valuable.

Retirement coaching recognises that leaving a firm can involve a fundamental shift in identity, status, purpose and daily life, alongside practical questions about what comes next.

A senior partner may spend their career advising others while having very little space to consider their own future. A confidential, independent coaching relationship provides that space.

It allows them to explore questions they may not feel able to discuss openly within the firm:

  • What will I miss when I leave?
  • What parts of my professional identity do I want to retain?
  • What do I actually want to do next?
  • Do I want to work differently rather than stop altogether?
  • How do I want to use the experience and reputation I have built?
  • What would a successful next chapter look like for me?

Good coaching can then turn those reflections into practical action — whether that means exploring non-executive or trustee roles, mentoring, social-impact work, a portfolio career, new networks or simply creating structure and purpose for life beyond the firm.

Most importantly, it can help a partner move from thinking about what they are leaving to what they are moving towards.

That can benefit the firm too. Someone who has prepared psychologically, as well as practically, is better placed to engage constructively with succession, client handover and knowledge transfer..

Retirement can be a strength, not a disruption

Handled well, partner retirement can become a positive transition for everyone.

Clients experience continuity. The next generation gets genuine opportunities. Knowledge is retained. The retiring partner leaves with confidence and dignity. And the firm may retain a respected former partner who continues to contribute through mentoring, introductions, referrals, board roles or simply by being an advocate for the business.

At Futurum Group, we use the term Encore because we believe the end of a legal career does not have to mean the end of contribution, purpose or professional identity. Our work helps experienced professionals prepare not just for what they are leaving, but for what they want to move towards.

The question for law firm leaders is not simply:

“Is our partner ready to retire?”

It is: “Are we ready for them to leave, and have we given both the firm and the individual enough time and support to make the transition a success?”

Download our free White Paper.

About the authors

Futurum Group Ltd was founded by Graeme Menzies & Sarah Harrison in 2020. They advise firms on how to successfully navigate the business-critical issue of partner retirements. Their approach is founded in Graeme’s experience of retiring after 30 years as a partner with a major law firm and Sarah’s 20 years in communications and employee engagement. They are ILM Level 7 Qualified Retirement Coaches. 

futurumgroup.co.uk

sarah@futurumgroup.co.uk 07581148550

graeme@futurumgroup.co.uk 07771564520 

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“I’ve been a client of Cashroom for over 10 years and couldn’t fault the service. When I started the firm, I had basic knowledge of compliance and bookkeeping but didn’t feel confident managing it myself. Cashroom took that weight off my shoulders and provided an invaluable resource I wouldn’t have been able to afford in-house.”

Mubasher Choudry
Mubasher Choudry
Mubasher Choudry Family Law Solutions

Compliance Doesn’t Have to Slow Your Firm Down

Compliance in many firms can be something that comes into focus when a deadline is approaching or an issue needs to be resolved. It’s often associated with additional administration, detailed record keeping and processes that can feel like they’re slowing everything down. With increasing regulatory requirements and growing client expectations, it’s understandable why some firms see compliance as another pressure on an already busy finance function. 

However, compliance doesn’t have to be and should never be a separate task that competes with the day-to-day running of the business. When finance processes are well designed and consistently followed, meeting regulatory obligations becomes part of normal operations rather than an added burden. Good compliance is often the result of good financial management, with clear processes, accurate records and effective oversight working together to reduce risk and improve efficiency. 

Many of the controls required to protect client money also help firms run more effectively. Completing reconciliations on time, maintaining accurate records and following robust approval processes all contribute to a finance function that is organised and reliable. When these activities are embedded into everyday workflows, finance teams spend less time resolving errors or chasing missing information, while partners benefit from greater confidence in the firm’s financial controls. 

Technology has also changed the way firms approach compliance. Automated bank feeds, digital payment approvals and integrations with practice management systems have reduced the need for manual administration while creating stronger audit trails and improving visibility over financial activity. These tools help finance teams complete routine tasks more efficiently, but they are most effective when combined with experienced legal finance professionals who understand the regulatory requirements and can apply their judgement when situations fall outside the norm. 

Another important consideration is resilience. Many firms still rely on one or two key individuals to manage essential finance tasks, creating unnecessary risk if someone is absent or leaves the business. By documenting procedures, sharing knowledge and ensuring there is appropriate support available, firms can maintain continuity without compromising compliance. Building resilience into the finance function not only strengthens internal controls but also gives firms the flexibility to adapt as they grow. 

Ultimately, compliance should be viewed as an investment in the firm’s long-term success rather than simply a regulatory obligation. Strong financial controls protect client money, provide reliable financial information and give partners the confidence to make informed decisions. They also create a more efficient working environment, allowing finance teams to focus on supporting the wider business instead of spending valuable time correcting avoidable issues. 

Of course, every law firm is different, and the level of support needed will vary. Some firms may simply need additional resource during busy periods, while others may benefit from a fully outsourced legal finance function. Whatever the requirement, having access to experienced legal finance professionals can help ease the pressure on internal teams while ensuring compliance remains a priority. 

At Cashroom, we help law firms build finance functions that support both compliance and day-to-day operations. Our team combines specialist legal finance expertise with proven processes to help firms meet their regulatory obligations while operating efficiently. By taking the pressure out of legal finance, we help firms strengthen compliance and improve efficiency, giving them the confidence that their finance function is supporting, rather than slowing down their business.  

If you’d like to find out how Cashroom could support your firm, we’d be happy to discuss your requirements and how we can help.

Contact Us

Need Support with Legal Accounting?

Cashroom specialises in outsourced accounting services for law firms across the UK, helping firms stay compliant, efficient and financially informed.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

Law Firms and Money

Would you believe that some law firms still manage their cashflow by ‘checking their bank statements’?

It’s an extreme version, but it exemplifies what we regularly encounter. The fear of change inherent in the lawyer’s mentality (I know because I was one for a long time!) can lead to a chain of issues.

“Always done things this way.”

“Changing technology or process will be too difficult.”

When you look at such attitudes in detail, this can mean that law firms don’t optimise their operations, both in relation to client work and in relation to the crucial accounts (client and office) part of their firm.

Every element of successful operation can be impacted by this- not least, the simple day to day viability of the firm from a financial performance perspective.

Is the quote for the client based on good assessment of what it will take to do the job profitably?

Is the handling and recording of client money being done efficiently, accurately and compliantly?

Is billing happening at all, or promptly?

Is credit control in place to ensure that those bills are paid?

Even when all those things are done well- is the available data being used to manage the business. Real time accurate data is invaluable, as it provides the opportunity to create meaningful cashflow calculations on a daily, weekly or monthly basis. It means the firm can understand (as per the regulatory requirement by the way!) whether they are in fact operating a viable business.

How can a firm make decisions to invest in people or tech if they don’t have accurate data enabling them to assess whether they have the funds to make those moves?

If we look at the overall topic of ‘money’ for lawyers, it has so many connotations. It leads to regulatory thinking where client money is concerned. It comes into recruitment- are you paying the right salaries to attract and retain talent?

In the end though, the general principle that “money is important to lawyers” is a trite and unhelpful statement. Far better perhaps to pose a question to the law firms- do you understand the state of your firm’s finances? Do you understand whether you are compliant and risk avoidant in your handling of client and firm money?

If in doubt on either point, it’s crucial that an investment of time initially is made to look into it. Before it’s too late.

About the author

Alex Holt, Chief Revenue Officer at The Cashroom, has over 30 years’ experience in the legal sector, including as a law firm partner. He brings deep expertise in law firm operations, financial management, and strategic growth, helping firms optimise processes, improve efficiency, and navigate change while delivering exceptional client service.


Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“I’ve been a client of Cashroom for over 10 years and couldn’t fault the service. When I started the firm, I had basic knowledge of compliance and bookkeeping but didn’t feel confident managing it myself. Cashroom took that weight off my shoulders and provided an invaluable resource I wouldn’t have been able to afford in-house.”

Mubasher Choudry
Mubasher Choudry
Mubasher Choudry Family Law Solutions

Signs Your Legal Finance Function Isn’t Fit for Purpose

In many law firms, the finance function doesn’t feel broken. It feels… stretched. Things are getting done. Payments are processed. Reports go out. There’s no obvious crisis. And yet, underneath the surface, there’s a sense that everything is taking more effort than it should. Processes rely on workarounds, that pressure is building, and that if something unexpected happened, it could quickly become a problem. 

That’s what an unfit finance function looks like in reality.   

When Control Starts to Slip 

One of the earliest signs is a loss of real, day-to-day control. On paper, everything appears to be in order. But in practice, visibility is delayed. Financial positions are confirmed after the fact, not in real time. Confidence in the numbers depends on when they were last reviewed, rather than an underlying certainty that everything is correct as of now. 

This often happens gradually. As firms grow, transaction volumes increase, complexity builds, and processes that once worked begin to strain. What used to take an hour now takes half a day. What used to be checked daily is now reviewed weekly. Nothing feels dramatically different, but the gap between activity and oversight starts to widen. 

 And that gap is where risk lives. 

When Processes Become Person-Dependent 

Another clear indicator is reliance on individuals rather than systems. Every firm has experienced team members who hold deep knowledge of how things work. That isn’t a problem, but the issue arises when that knowledge becomes the process. 

When only one person knows how to resolve discrepancies, when queries always route back to the same individual, or when holidays create disruption rather than continuity, it points to a finance function that hasn’t been properly structured. This creates more than just operational inefficiency. It introduces a single point of failure, because no matter how capable someone is, a function that depends on them entirely is not resilient. 

When Audit Readiness Becomes Reactive 

Audit pressure is often where underlying weaknesses become visible. In a well-functioning finance environment, an audit is simply a formal review of processes that are already working as they should. There is no scramble, no last-minute fixes, no uncertainty about whether everything will stand up to scrutiny. But in many firms, the reality is very different. 

Audit preparation becomes a concentrated period of stress. Time is spent pulling together information, checking historical entries, and resolving issues that should have been addressed earlier. Teams work harder, not because the audit itself is difficult, but because the underlying processes haven’t been designed to support it. That shift, from being ready, to needing to get ready, is a strong signal that something isn’t quite right. 

When Errors Are Inevitable, Not Occasional 

No finance function is completely error-free. But there’s a difference between occasional mistakes and a system that allows errors to pass through unnoticed. 

When issues are picked up late, or worse, by external parties, it suggests that controls are either too light or inconsistently applied. Often, this is tied to manual processes. The more touchpoints there are, the more opportunity there is for something to be missed, especially under pressure. 

Over time, teams begin to compensate. They double-check more. They spend longer reviewing work. They rely on experience and instinct to catch issues. It slows everything down and still doesn’t guarantee consistency. 

When Finance Becomes a Drain on Time 

One of the less obvious, but equally important signs is the amount of time the finance function consumes across the business. 

It’s not just about the finance team. It’s about how often fee earners, managers, or leadership have to get involved. How frequently questions arise. How much time is spent chasing clarity, resolving queries, or waiting for answers. A fit-for-purpose finance function should reduce friction, not create it. 

When it’s working properly, it operates in the background, providing clarity and support without demanding constant attention. When it isn’t, it becomes something the wider business must work around. 

When Decision-Making Lacks Confidence 

Perhaps the most telling sign is how finance information is used. If leadership hesitates before relying on reports, if decisions are made with caveats, or if there’s a tendency to sense-check figures rather than trust them, it indicates a lack of confidence in the underlying data. 

That lack of confidence doesn’t always come from major issues. More often, it’s the result of small inconsistencies over time, delays, adjustments, minor discrepancies that gradually erode trust. 

And without trust in the numbers, finance stops being a strategic asset. It becomes a source of uncertainty. 

The Point Where “Good Enough” Stops Working 

Many finance functions reach a stage where they are technically functioning but no longer fit for the firm they support. They were built for a smaller, simpler operation. As the firm grows, they are adapted rather than redesigned. New processes are layered on top of old ones. Workarounds become standard practice. 

For a while, this holds together but eventually, the gap between what the firm needs and what the finance function can reliably deliver becomes too large to ignore. That’s usually when problems become visible. Not because something suddenly changed, but because the existing setup has been stretched beyond its limits. 

A Different Standard 

A fit-for-purpose legal finance function doesn’t just process transactions or produce reports. It provides assurance. It allows firms to operate with confidence that client money is being handled correctly, that compliance obligations are consistently met, and that financial information reflects reality, not approximation. It is structured, repeatable, and visible. It doesn’t rely on last-minute effort or individual knowledge to hold things together. 

And importantly, it scales. It supports growth rather than being strained by it. 

Final Thought 

Most firms don’t deliberately build a finance function that falls short. It happens over time, shaped by growth, resource constraints, and immediate priorities. 

Recognising that point early before pressure turns into problems is what separates firms that stay in control from those that are forced to react. When it comes to legal finance, the real risk isn’t what’s already gone wrong. It’s what hasn’t been uncovered yet. 

Is your finance function supporting your firm’s growth, or holding it back?

If any of these signs sound familiar, it may be time to take a closer look at how your legal finance function is operating. Whether you need additional expertise, greater resilience, or simply an objective review of your current processes, Cashroom can help you build a finance function that is compliant, scalable, and fit for the future. Get in touch with our team to discuss how we can support your firm. 

Need Support with Legal Accounting?

Cashroom specialises in outsourced accounting services for law firms across the UK, helping firms stay compliant, efficient and financially informed.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

Is Your Pension Working as Hard as You Are?

Guest blogger: Ben Williams

Working with self-employed solicitors, consultants and legal professionals, we often see the same challenge. Retirement planning is something that people know is important, but it’s rarely urgent. Between managing clients, running a practice and keeping on top of compliance, pensions can easily be pushed to the bottom of the list.

It’s understandable. Legal professionals spend their careers helping others plan ahead and manage risk, yet many don’t apply that same level of planning to their own financial future.

One of the most common things we come across is professionals with several pension pots built up over the course of their career. They may have a workplace pension from when they were employed, another from a previous firm and perhaps a personal pension they’ve been contributing to since becoming self-employed. Often these pensions haven’t been reviewed for many years and, in some cases, people aren’t even sure exactly what they have.

While having multiple pensions isn’t necessarily a problem, it’s important to understand whether they’re still appropriate for your circumstances. Investment performance, charges and retirement objectives can all change over time, and a pension that suited you ten years ago may not be the best fit today.

Another common misconception is that retirement planning is simply about accumulating the biggest pension pot possible. In reality, it’s about creating a plan that can provide the level of income you’ll need throughout retirement. For self-employed professionals, whose income may fluctuate from year to year, this often requires a more tailored approach.

Pensions also remain one of the most tax-efficient ways to save for the future. Making regular contributions, particularly during profitable years, can form an important part of wider financial planning while helping you build long-term financial security. Regular reviews can also ensure your pension strategy continues to reflect changes in your business, personal circumstances and retirement goals.

Having worked as a financial adviser for more than 10 years, I’ve had the privilege of helping individuals, business owners and legal professionals build their pensions and work towards the retirement they want. One thing I’ve learned is that no two clients are the same. The most effective retirement plans are those that are tailored to an individual’s objectives, rather than relying on a one-size-fits-all solution.

The legal profession is built on careful planning, attention to detail and preparing for the future. Applying that same mindset to your own retirement can make a significant difference. Taking the time to review your existing pensions, understand where you stand and put a clear plan in place today can provide greater confidence for tomorrow.

After all, your pension should be working just as hard as you do.

About the author

Ben Williams

Ben Williams is a Wealth Management Partner at True Potential Wealth Management, helping individuals and businesses protect, grow and preserve their wealth through tailored financial planning. Ben takes the time to understand each client’s goals and provides clear, practical advice, giving them the confidence to make informed financial decisions and build long-term financial security.

Contact Ben

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“I’ve been a client of Cashroom for over 10 years and couldn’t fault the service. When I started the firm, I had basic knowledge of compliance and bookkeeping but didn’t feel confident managing it myself. Cashroom took that weight off my shoulders and provided an invaluable resource I wouldn’t have been able to afford in-house.”

Mubasher Choudry
Mubasher Choudry
Mubasher Choudry Family Law Solutions

Technology, Integration, and The Future of Legal Finance

For many law firms, finance has traditionally sat in the background, often disconnected from the systems and processes that drive day-to-day legal work. However, this is becoming less sustainable. As firms look to improve efficiency, reduce risk, and gain better visibility over  performance, outsourced legal finance and the role of technology in legal finance are becoming more central to modern operations. By combining specialist support with connected systems, firms can streamline processes, reduce errors and focus on delivering value to clients. 

CEO of Cashroom, Chris O’Day explains that outsourced legal finance works best when it feels like a natural extension of the firm and not a separate function. 

Q. The Cashroom now works with more than 30 case and practice management systems. How crucial is seamless technology and integration to the future of outsourced legal finance, and to the experience firms receive?

A. Integration is absolutely central. If outsourced finance felt like a separate system bolted on at the side, it wouldn’t work. Our aim is that from the firm’s point of view, everything feels joined-up; matter data, client ledgers, banking, reporting and approvals all talking to one another. 

We’ve invested heavily in integrating our portal with the leading case and practice management systems, as well as with the banking network via open-banking connections and payment-verification tools. That means transactions can flow securely and accurately between systems, with far fewer manual touchpoints and far less scope for error. 

For firms, the benefits are very tangible. Fee-earners can see the financial position of matters in real time. Cashiers don’t have to rekey data between platforms. Approvers can authorise payments from wherever they are, with the right controls around them. And partners get clearer management information, faster. 

 Seamless integration is what will allow us to bring more automation and AI into the process without compromising control. If the data is structured and connected, you can start to automate the routine tasks – posting, matching, exception-flagging – while keeping humans focused on judgement, review and client communication. 

“Good technology isn’t a nice-to-have; it’s what turns outsourced finance from a service into part of a firm’s core infrastructure.” 

Q. Looking ahead, how do you see legal finance operations evolving over the next decade, especially with AI, automation, and regulation all accelerating at once?

A. I think we’ll see three big shifts.

First, the routine mechanics of legal finance will become increasingly automated. Posting transactions, matching payments, flagging anomalies and generating standard reports are all tasks that lend themselves to smart automation and, in time, AI. That won’t remove the need for humans, but it will change their role, from data entry to oversight, exception handling and interpretation. 

Second, firms will demand better, more real-time insight. Rather than waiting for month-end packs, they’ll want live visibility of cash, WIP, lock-up and matter profitability, across the entire firm and down to individual teams. That requires clean, connected data across practice management, banking and finance platforms – which is where integrated outsourced models can add real value. 

Third, regulation will continue to evolve, often in response to technology itself – whether that’s around open banking, new payment methods, or emerging risks like sophisticated fraud. The direction of travel is clear: regulators expect firms to be proactive, well-informed and able to evidence strong control environments, particularly around client money. 

In that world, I see outsourced legal finance becoming even more embedded. It’s difficult for individual firms to keep pace with advances in technology, regulatory change and talent development on their own. Partnering with a specialist that sits at the intersection of those trends, and spreads the investment across hundreds of firms, is a pragmatic way to stay ahead. 

My hope is that, ten years from now, legal finance will feel less like a constant source of pressure and more like a strategic asset that helps firms grow with confidence. 

Building a Smarter, More Resilient Finance Function 

The future of legal finance is clearly tied to technology, integration, and smart, connected processes. Firms that embrace these changes will not only improve efficiency and accuracy, but also gain the real-time insight and resilience needed to navigate growth, regulatory change, and operational complexity. 

Outsourced legal finance, when seamlessly integrated into a firm’s systems, becomes part of the firm’s core infrastructure than just a back-office function. It frees teams to focus on higher-value work, empowers partners with clear, actionable data, and ensures client funds are managed safely and efficiently. 

By investing in integrated technology and specialist outsourced support, law firms can turn legal finance from a source of stress into a strategic advantage, building a foundation that supports sustainable growth, confident decision-making, and long-term success. 

Discover how outsourcing and integrated technology can transform your legal finance function. 

Learn how Cashroom helps law firms streamline processes, improve accuracy, and gain real-time insight, freeing your team to focus on clients, growth, and strategy. 

About Chris O’Day

Chris O’Day is a Chartered Accountant, having qualified at Deloitte and has had a significant impact at Cashroom over the years since joining in 2014. After joining Cashroom as a Management Accountant, his extensive experience in legal accounting saw him become Cashroom’s Client Services Director in 2017 – gaining significant insight as to what is valuable to clients and to the legal industry, before taking on the CEO role in 2021 to drive the next phase of Cashroom’s growth. 

Chris finds endless opportunities and has a key focus on challenging the status quo in order to drive continuous improvement across the business and the services Cashroom provide to the Legal Sector. Chris believes that being client-centric is key to any service business – understanding what lawyers want and need and ensuring Cashroom deliver the best customer experience that is efficient, compliant and risk-free.

Learn how Cashroom can help your firm build a finance function that’s both secure and scalable.  

Contact Us

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“I’ve been a client of Cashroom for over 10 years and couldn’t fault the service. When I started the firm, I had basic knowledge of compliance and bookkeeping but didn’t feel confident managing it myself. Cashroom took that weight off my shoulders and provided an invaluable resource I wouldn’t have been able to afford in-house.”

Mubasher Choudry
Mubasher Choudry
Mubasher Choudry Family Law Solutions

Financial Red Flags Every Managing Partner Should Watch For

For many managing partners, the focus of the working day is naturally on clients, people and keeping the firm moving forward. If you’re lucky, you might find some time for business development too.

Outside of work, life is rarely any quieter. Whether its school runs and family commitments, caring responsibilities for ageing parents, or simply juggling the demands of everyday life, there’s a lot competing for your attention.

With so much going on, it’s understandable that the financial management of the firm can become something that sits quietly in the background. You review the management accounts at monthly partner meetings, year-end accounts are prepared, compliance requirements are met, and you trust that everything is under control.

The reality, however, is that financial problems rarely appear overnight.

They tend to develop gradually through small inefficiencies, delayed decisions or processes that no longer reflect the way the firm operates. By the time they become visible, they may already be affecting profitability, cash flow or regulatory compliance.

The challenge is recognising the warning signs early.

When Cash Flow Feels Tighter Despite a Healthy Workload

One of the most common frustrations for law firms is the disconnect between how busy the practice feels and how much cash is actually available.

A full diary and a growing caseload do not automatically translate into healthy cash flow. Work in progress may remain unbilled for longer than expected, invoices may not be issued promptly, or outstanding debts may continue to increase. Meanwhile, payroll, supplier invoices and other operating costs still need to be met.

Many firms find themselves asking the same question: “If we’re so busy, why doesn’t the bank balance reflect it?”

Regular cash flow forecasting helps identify these issues before they become problematic. Rather than simply reviewing what has already happened, firms can understand what is likely to happen over the coming weeks and months, allowing them to make informed decisions with greater confidence.

Your Financial Reports Arrive, But They’re Already Out of Date

Management information is only valuable if it helps you make decisions.

If partners are reviewing reports several weeks after month end, they are often reacting to information that is already out of date. Instead of driving decisions, reporting becomes little more than a compliance exercise.

Law firms generate significant amounts of financial information every day. Billing, client receipts, supplier payments and payroll all contribute to a constantly changing picture. Timely, accurate reporting enables partners to spot trends early and respond before small issues become larger problems.

Good reporting should do more than present numbers. It should explain what those numbers mean, highlight unusual movements and provide genuine insight into the firm’s financial performance.

Increasing Lock-up Quietly Restricts Growth

Lock-up is discussed regularly within legal finance, but its impact is often underestimated.

Every pound tied up in unbilled work or unpaid invoices is money that cannot be invested elsewhere in the business. As lock-up increases, firms may delay investment in technology, recruitment or business development despite appearing profitable on paper.

Bills may not be raised promptly, matters may remain open unnecessarily, or credit control may become inconsistent during busy periods. Individually these delays seem manageable, but collectively they can place significant pressure on cash flow.

Regularly reviewing lock-up and understanding where delays occur allows firms to release working capital without increasing fees or taking on additional work.

Compliance Should Never Become an Afterthought

Financial compliance cannot simply become a focus in the weeks before an audit or regulatory inspection.

Maintaining accurate financial records, robust internal controls and timely reconciliations should form part of everyday operations. Strong financial governance protects client money, reduces risk and provides confidence that issues will be identified before they become significant.

Where finance teams are stretched or processes rely heavily on manual intervention, reconciliations are more likely to be delayed, and discrepancies can take longer to identify.

The strongest firms build compliance into their day-to-day processes rather than treating it as an administrative exercise at month end.

“Outsourcing acted as an important risk management tool. Partnering with experts like Cashroom, reduced the risks of errors and ensured strong compliance processes from day one.” – Stacy Campbell | McKee Campbell Morrison Solicitors

Manual Processes Become Hidden Barriers

As firms grow, finance teams often inherit additional responsibilities without receiving additional resource.

Processes that worked perfectly for a smaller practice can quickly become inefficient as transaction volumes increase. Payment processing, reconciliations, reporting and administration all require more time, while expectations around accuracy and compliance remain unchanged.

Over time, highly skilled finance professionals can spend most of their day completing repetitive administrative tasks instead of providing the financial insight that partners genuinely need. It’s also one of the reasons experienced finance professionals can become disengaged and eventually leave, creating further operational challenges.

Reviewing workflows and making better use of technology or specialist legal finance support allows finance teams to focus on higher-value work while improving efficiency and reducing operational risk.

Perhaps the biggest warning sign of all is when financial performance consistently comes as a surprise.

Partners should understand how the business is performing throughout the year, not just when annual accounts are prepared.

If profitability is lower than expected, overheads continue to rise without explanation, or cash flow regularly causes concern despite a healthy pipeline of work, these are all indicators that greater financial visibility is needed.

Good financial management isn’t simply about producing reports. It’s about providing timely information that enables better decisions, supports future planning and gives firms confidence to navigate an increasingly complex legal landscape.

Looking Ahead

Financial resilience is built through consistent processes, accurate reporting and proactive oversight. Most financial challenges begin as small operational issues that, if left unresolved, gradually become much larger business risks.

By recognising these early warning signs, firms can strengthen financial performance, improve compliance and put themselves in a stronger position for sustainable growth.

At Cashroom, we work exclusively with law firms across Scotland and the rest of the UK, helping practices strengthen financial processes, improve compliance and gain greater visibility over their financial performance.

As an approved supplier of the Law Society of Scotland, we understand the specific regulatory requirements facing Scottish law firms. Whether supporting sole practitioners or multi-office practices, our experienced legal finance professionals work alongside existing teams to deliver accurate financial management, robust compliance and the insight firms need to make confident business decisions.

Need Support with Legal Accounting?

Cashroom specialises in outsourced accounting services for law firms across the UK, helping firms stay compliant, efficient and financially informed.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

Choosing an Accountant for Your Law Firm

Lawyers are trained to practice law, not accounting, but poor financial management can have serious consequences for a firm’s performance.

From client account compliance to cash flow management, legal finance comes with strict regulatory requirements. Choosing the right accountant helps protect you firm, your clients and your professional reputation.

So, how do you choose the right accountant for your law firm?

Why Legal Accounting Expertise Matters

Legal accounting isn’t the same as standard business accounting.

Law firms must comply with the Solicitors Regulation Authority (SRA) Accounts Rules, particularly when handling client money. This includes:

  • Keeping client money separate from office funds
  • Ensuring accurate, timely and fully reconciled client account records
  • Maintaining clear audit trails for all transactions
  • Preventing breaches that could lead to regulatory investigation

For example, even something as simple as a delay in reconciling client account transactions can create compliance issues if discrepancies are not identified and corrected promptly.

Incorrect handling of client funds can result in fines, intervention, reputational damage, or in serious cases, regulatory action against the firm or individuals involved.

This is why working with an accountant who specialises in the legal sector is essential. It ensures your financial processes are compliant, controlled, and aligned with regulatory expectations, while also maintaining the trust your clients place in you.

What to Look for in a Legal Accountant

1. Proven Experience in the Legal Sector

Not all accountants understand the nuances of legal finance.

A general practice accountant may be comfortable with small business bookkeeping, but legal finance requires specialist knowledge of client money rules, billing structures, and regulatory reporting.

Look for a provider that:

  • Works specifically with law firms
  • Understands your firm’s compliance requirements, whether that’s the Solicitors Regulation Authority (SRA), Law Society of Scotland, or the Council for Licensed Conveyancers (CLC)
  • Has experience with your type of firm (e.g. conveyancing, litigation, family law)

A conveyancing-heavy firm will have high volumes of client transactions requiring frequent reconciliations, whereas a litigation practice may need more complex work-in-progress tracking and billing oversight.

Knowledge from a specialist legal accountant will understand these difference and tailor their approach accordingly.

2. Strong Compliance and Risk Management

Compliance is a critical part of your firms’ operations and goes far beyond simple box ticking.

Your accountant should:

  • Monitor compliance with SRA Accounts Rules on an ongoing basis
  • Carry out regular three-way reconciliations of client accounts
  • Identify unusual transactions or discrepancies early
  • Help ensure breaches are prevented, not just reported after the fact

If a client account is not reconciled promptly, a specialist accountant would flag this early and help resolve it before it becomes a compliance breach.

This proactive approach reduces regulatory risk and gives you confidence that your firm’s finances are being managed correctly.

3. Technology That Works with Your Firm

Modern law firms rely on technology to operate efficiently, from practice management systems to cloud-based accounting tools.

Your accountant should be comfortable working within your existing systems, rather than forcing you to change them.

Look for experience with:

  • Practice management systems such as LEAP, Proclaim, or Clio
  • Cloud accounting platforms like Xero or QuickBooks
  • Secure, real-time reporting and document sharing tools

For example, integration between your practice management system and accounting processes can significantly reduce manual data entry, improve accuracy, and speed up month-end reporting.

Cashroom, for instance, works system-agnostically and uses The Cashroom Portal to integrate with a firm’s existing systems, meaning firms can retain their current infrastructure while still accessing specialist legal accounting support.

4. Scalable Support as You Grow

As your firm grows, so will your accounting needs.

You may start with basic bookkeeping needs, but over time require more advanced support such as management accounts, payroll, credit control, and financial forecasting.

A strong provider should be able to scale with you by offering:

  • Flexible service levels that adjust to your firm’s needs
  • Additional support functions such as payroll and credit control
  • Strategic financial insight, not just transactional processing

A growing firm opening a second office may need consolidated management accounts across locations, along with clearer visibility of profitability by department or fee earner. Outsourced accounting provides access to a full team of specialists without the cost and complexity of building an in-house finance department.

5. Clear Reporting and Commercial Insight

A good accountant goes beyond reporting figures, providing clarity and insight into what they mean for your firm.

You should expect:

  • Regular, structured financial reporting
  • Cash flow forecasting and visibility of upcoming commitments
  • Profitability analysis by matter type, department, or fee earner
  • Clear commentary that explains what the numbers mean

Understanding that a department is highly active but low in profitability may highlight pricing issues, inefficiencies, or billing delays that need to be addressed. This level of insight enables better decision-making and supports sustainable growth.

Questions to Ask Before You Choose

Before appointing an accountant, ask:

  • Do you specialise in working with UK law firms?
  • How do you ensure compliance with SRA Accounts Rules?
  • What systems do you integrate with, and how does the process work?
  • What level of reporting and support will I receive?
  • How will your service scale as my firm grows?

The quality and specificity of the answers will quickly reveal whether the provider truly understands legal finance or offers a generic accounting service.

In-House vs Outsourced: What’s Right for Your Firm?

Many firms attempt to manage financial operations internally, often combining fee-earning staff with administrative or part-time finance roles.

While this may work in the short term, it often creates challenges such as:

Outsourcing your legal accounting function offers a different approach.

It provides:

Final Thoughts

Choosing the right accountant is one of the most important decisions you’ll make for your firm.

The right partner will:

  • Ensure compliance
  • Improve financial clarity
  • Support your growth

The wrong one can lead to inefficiency, unnecessary risk and avoidable stress.

Taking the time to choose carefully now can make a significant difference to your firm’s long-term success.

Need Support with Legal Accounting?

Cashroom specialises in outsourced accounting services for law firms across the UK, helping firms stay compliant, efficient and financially informed.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

Cashroom Becomes a Clio EMEA Gold Certified Partner

Leading legal finance provider strengthens strategic partnership with Clio to help law firms improve efficiency, compliance, and financial visibility.

Cashroom is delighted to announce that it has become Clio’s first EMEA Gold Certified Partner, marking a significant milestone in the long-standing relationship between the two organisations. 

The achievement recognises Cashroom’s expertise in legal finance and its commitment to helping law firms maximise the benefits of legal technology through the seamless integration of Cashroom’s specialist accounting services and Clio’s leading cloud-based practice management platform. 

As one of the UK’s leading providers of outsourced legal cashiering, management accounts, payroll and financial services for law firms, Cashroom works with more than 300 firms across the UK, providing compliant, scalable finance support backed by innovative technology. 

The partnership between Cashroom and Clio enables law firms to streamline legal accounting processes, reduce administrative burden, improve compliance, and gain greater visibility over their financial performance. Through the integration between Clio and the Cashroom Portal, firms benefit from more efficient workflows, reduced risk of error, and access to real-time financial information. 

Emma O’Day, CMO of Cashroom, said: 

“Achieving Gold Certified Partner status with Clio is a fantastic milestone for Cashroom and reflects the strength of our relationship with the Clio team. We share a commitment to helping law firms embrace technology, improve efficiency, and build stronger, more resilient businesses. 

As legal practices continue to grow, firms need trusted partners who can help them navigate both operational and financial challenges. By combining Clio’s market-leading practice management platform with Cashroom’s specialist legal accounting expertise, we are helping firms create a more streamlined, secure and scalable future.” 

The recognition further strengthens Cashroom’s position as a trusted technology and finance partner for law firms and reinforces its commitment to investing in integrations and partnerships that deliver practical value to clients. 

Myles McLaren, EMEA Channel Lead at Clio, said: 

“Cashroom has demonstrated a strong commitment to helping law firms succeed through technology, operational excellence and financial expertise. We are delighted to recognise their achievements as our newest EMEA Gold Certified Partner and look forward to continuing to support law firms together.” 

The announcement comes as increasing numbers of law firms look to modernise their operations, improve compliance, and create more efficient ways of working. Together, Cashroom and Clio provide firms with an integrated solution that supports growth while reducing risk and administrative complexity. 

Readers can learn more about Cashroom’s certification and partnership with Clio here. 

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“We have used Cashroom for many years, it’s a great system. Our firm is regularly instructed to support significant transactions – both in terms of the importance of deals, as well as their value. As a result, we need to be absolutely sure that we can rely and trust on our finance management partners to be able to administer fast, secure, and seamless transactions. We’ve never thought to look elsewhere as Cashroom have always been there for us.”

Sharon Needle
Sharon Needle
Needle Partners Limited

SRA Effective Supervision Guidance

Guest blogger: The Compliance Office

The SRA’s updated Effective supervision – Guidance was finally published on 12th June 2026.

This follows the Court of Appeal’s much-heralded ‘conduct of litigation’ judgment in the Mazur case in March (see some of our previous thoughts here). By way of a reminder, the Court of Appeal concluded that it is lawful for an unauthorised person to carry out work amounting to the ‘conduct of litigation’ under the Legal Services Act 2007 (LSA) as long as they are doing so ‘for and on behalf of an authorised individual’ under their genuine and effective supervision, including providing ‘proper direction, management, supervision and control’. The Court however, left the detail of what effective supervision looks like to legal regulators, such as the SRA. The much-anticipated guidance from the SRA has now landed!

The Law Society updated its practice note on ‘Mazur and the conduct of litigation’ in April. It has taken the SRA longer to produce its updated guidance due to it working with other representative bodies, including the Law Society and CILEX Regulation, as well as government departments,
the Legal Aid Agency and the Law Centres Network to ensure a joined-up approach.

The SRA’s guidance has been significantly expanded (from 9 pages to 24 ) to deal with the impact of the Court of Appeal’s decision on supervision arrangements for non-authorised staff (i.e. non-solicitors or non-authorised barristers/ legal executives), including a complete rewrite of the section specifically addressing the ‘conduct of litigation’, as well as taking the opportunity to update its thoughts on supervision more
generally.

SRA Guidance – key points/changes

Whilst there is no substitution for reading the guidance itself in full (and we very much encourage this), here are the main points we have picked out:

  • It does not create any new standards or requirements beyond those in legislation or the SRA’s current standards and regulations.
  • It summarises the Court of Appeal’s conclusions in relation to the conduct of litigation and supervision (but, slightly oddly, doesn’t mention the Mazur case by name), emphasising that the supervising authorised person retains all responsibilities in relation to the tasks performed by the unauthorised person and the professional principles flowing therefrom.
  • The key themes remain the same (but have been expanded):
    o The need for supervision – to comply with SRA standards and regulations and the LSA
    o Appropriate supervision arrangements – these remain risk-based with the acknowledgement that there is no single model of supervision. The idea being that the intensity of supervision will depend on the complexity of the legal matter, the likely impact on clients if things go wrong, and the experience of the person carrying out the work.
    o Conducting supervision – a supervisor needs sufficient contact with the supervisee and must see enough work to identify patterns of risk, as well as having effective knowledge of the matters being worked on.
    o Ensuring supervision is effective – including proactive steps so that supervision arrangements are clear and understood.
  • Who can supervise? Supervisors do not have to be partners or those with line management responsibilities, but who should be a supervisor should be decided taking a risk-based approach, taking into account the proposed supervisor’s expertise, skills, availability and ‘whether they are able, in practice, to exercise proper direction, management, supervision and control over the work being delegated with confidence’.
  • Appropriate supervision arrangements
    o Supervisors should establish when and how they will check the supervisee’s work – not necessarily just at the ‘final product’ stage, always remembering that when dealing with reserved legal activities (including the conduct of litigation), it is the authorised person who remains responsible for the work.
    o There are various good practice suggestions, including ensuring clarity about tasks being delegated, including to whom, and the expectations from both the
    supervisor and the supervisee, including the scope and limits of delegated authority, and including supervision discussions in performance reviews.
  • Do you have a speak-up culture? Whilst not new to the guidance, it is worth mentioning the (highly topical) reference to the importance of firm culture enabling staff to raise concerns and be supported if they are experiencing problems.
  • Document everything! Firms are expected to record their rationale when designing supervision systems and delegation arrangements, as well as supervisors/ supervisees being expected to keep records of supervision in action.
  • ‘Conduct of litigation’ section: This provides helpful guidance as to how and when tasks can be delegated to unauthorised people (commenting that the suggestions in this section can be applied to any supervision situation), and how to demonstrate the required supervision, including having proportionate audit and quality assurance measures to promptly address any issues or breaches identified.
  • What amounts to ‘conduct of litigation’? An annex has been added to tackle this tricky issue, given the lack of a definitive list, and the rather vague definition in the LSA (issuing proceedings before any court in England & Wales; the commencement, prosecution and defence of such proceedings; and the performance of any ancillary functions in relation to such proceedings). The annex references the need for ‘professional judgement’, the fact that it will not include purely clerical or mechanical activities, and the list of issues the Court of Appeal grouped together as being unlikely to fall within the definition, namely:
o Pre-litigation work
o Giving legal advice in connection with court proceedings
o Conducting correspondence with the opposing party on behalf of clients
o Gathering evidence
o Instructing and liaising with experts and counsel
o Signing a statement of truth in respect of a statement of case
o Signing any other document that the CPR permits to be signed by a legal representative, as defined by CPR Part 2.3.
  • When is a criminal offence committed? Interestingly, the guidance makes no direct reference to this (pursuant to section 14 LSA, namely, when a non-authorised person conducts litigation or does so under the supervision of a non-authorised person) other than to include a section on the possible defence to such criminal proceedings, nor
    the Court of Appeal’s clarification that having an ineffective system of supervision in place will be a matter for regulators rather than the criminal courts. However, the
    Enforcement section now covers what the SRA will do if they discover that an unauthorised person is in fact taking responsibility for tasks that amount to the conduct of  litigation (perhaps with an authorised person allocated to the matter in name only). The Law Society guidance is the place to turn for more detail about the criminal side of things.
  • Case studies: The original 2 case studies have now been joined by a further 4, mainly focussing on High Volume work (including looking at the ratios of supervisors to
    supervisees and the benefit of having clear systems and controls in place overseen by a solicitor), but also looking at the thorny issue of significantly experienced, but nonauthorised staff, (such as legal executives without practising rights) having to be supervised by far more junior, but authorised, solicitors. Sadly, the guidance isn’t particularly enlightening as to how to deal with this senior/ junior situation, concluding simply that “this situation can be managed”
  • Additional sections: Specific sections have been added to address supervisors not authorised by the SRA and supervision of Artificial Intelligence-assisted work.

What was already there?

For those of you who haven’t read the SRA’s supervision guidance in a while, don’t forget it already included some helpful sections, including those addressing:

  • What checks supervision should involve
  • Face to face supervision and how to deal with remote, hybrid and agile working
  • Supervising work outside an employment relationship
  • Supervising trainees
  • Claims management activities, Immigration and Legal aid work

What does it all mean?

Effective supervision is a balance of professional judgement and robust systems. By clearly defining delegation, maintaining active oversight, and recording your supervisory rationale, you can ensure your firm remains compliant with the post-Mazur landscape and the SRA’s updated expectations, as well as your obligation to act in the best interests of your clients. Time to review your supervision arrangements!

About the authors

Jen Dunlop

Jen joined the Compliance Office in 2021 as a Senior Risk & Compliance Consultant, quickly making her mark with her deep regulatory expertise and practical, solutions-driven approach. Her leadership skills and commitment to excellence saw her promoted to Head of Compliance, before stepping into the role of Managing Director in April 2025.

Jessica Irwin

Jess joined the Compliance Office in 2023, bringing over two decades of legal and compliance expertise. She qualified as a Solicitor in 2000 and spent 19 years as a litigator at a leading, long-established Thames Valley law firm. In 2019, she transitioned into the role of Compliance Manager at the same firm, working closely with the COLP and MLRO/MLCO to drive best practice and ensure full SRA compliance.

Interested in a confidential chat?

If you are considering outsourcing your legal cashiering, or just want to find out how it works, our team is here to help.

Contact us
Back to Blogs
Cashroom provides expert outsourced account services for law firms including legal cashiering, management accounts and payroll services. Our mission is to fee lawyers from the complexities of legal accounting by supporting the industry with accurate management information and allowing lawyers to do what they do best – practice law.

“I’ve been a client of Cashroom for over 10 years and couldn’t fault the service. When I started the firm, I had basic knowledge of compliance and bookkeeping but didn’t feel confident managing it myself. Cashroom took that weight off my shoulders and provided an invaluable resource I wouldn’t have been able to afford in-house.”

Mubasher Choudry
Mubasher Choudry
Mubasher Choudry Family Law Solutions

Privacy Settings
We use cookies to enhance your experience while using our website. If you are using our Services via a browser you can restrict, block or remove cookies through your web browser settings. We also use content and scripts from third parties that may use tracking technologies. You can selectively provide your consent below to allow such third party embeds. For complete information about the cookies we use, data we collect and how we process them, please check our Privacy Policy
Youtube
Consent to display content from - Youtube
Vimeo
Consent to display content from - Vimeo
Google Maps
Consent to display content from - Google